
Protecting Your Home in the Sweetest Place on Earth
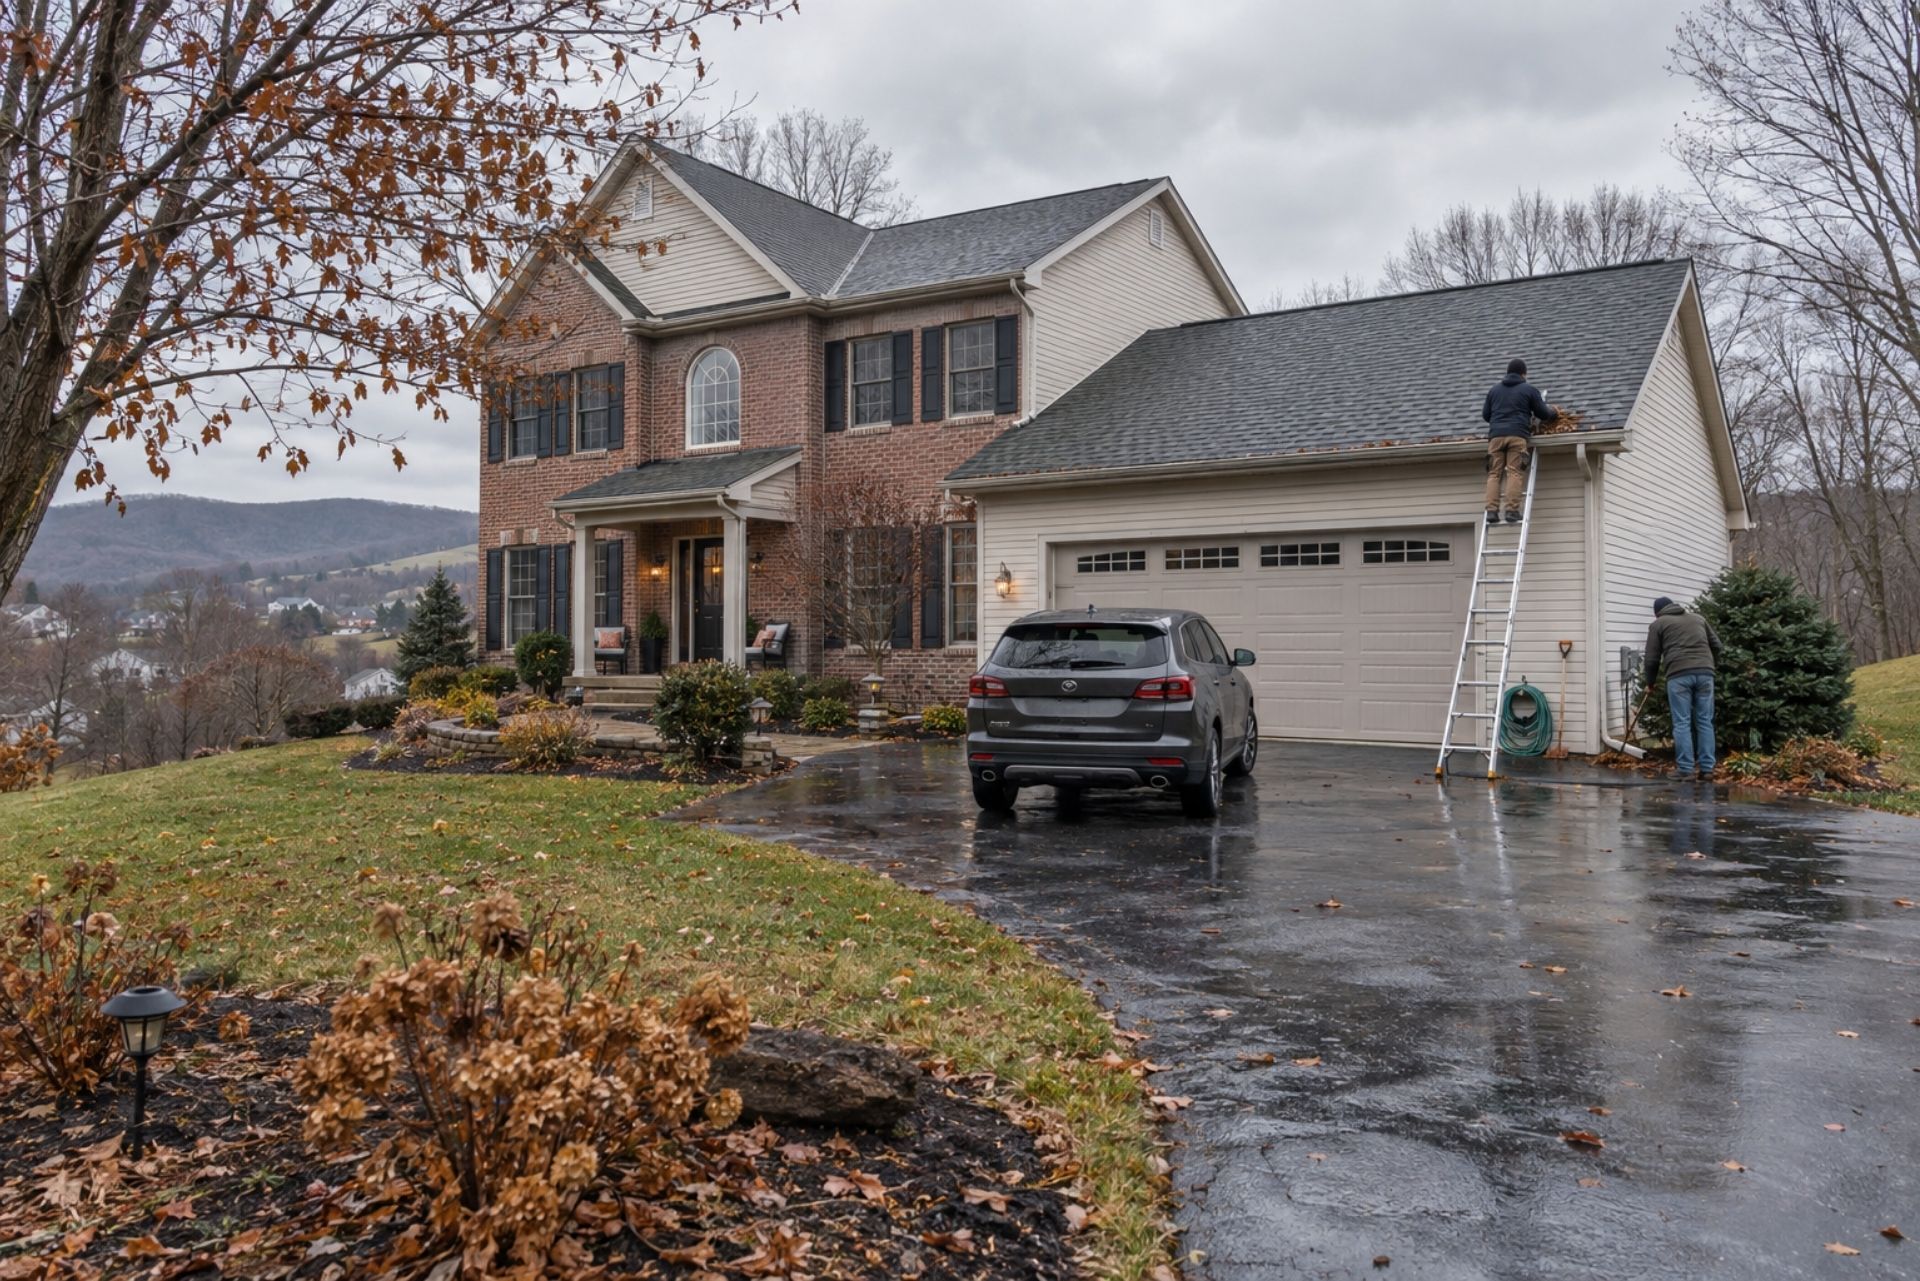
Hershey sits in Dauphin County, surrounded by rolling farmland, chocolate-scented breezes, and neighborhoods that range from century-old stone colonials to newer developments off Fishburn Road. It's a great place to own a home, but the region carries risks that don't always make the brochure: spring thunderstorms, aging municipal sewer lines, and winter ice dams that can quietly wreck a roof over a single season.
Pennsylvania homeowners pay an average annual premium between $1,200 and $1,893, which remains roughly 28% below the national average. That sounds like a bargain until you realize how quickly a gap in coverage can erase any savings. A single sewer backup claim can top $10,000, and an uninsured liability incident on your property could cost far more.
Understanding
home insurance in Hershey means knowing exactly what dwelling coverage, personal property limits, liability protection, water damage endorsements, deductibles, and available discounts actually do for you. Each piece of your policy plays a distinct role, and getting one wrong can leave thousands of dollars on the table, or worse, leave you exposed after a loss. This guide breaks down every component so you can build a policy that fits your home, your budget, and the specific risks that come with living in central Pennsylvania.
By: Tyler Reitz
Managing Principal of Bowmans Insurance
Core Coverage: Dwelling and Personal Property
Your homeowners policy rests on two pillars: the structure itself and everything inside it. These two coverages work together, but they're calculated differently, and mistakes on either side are common.
Insuring Your House Structure (Dwelling)
Dwelling coverage pays to rebuild or repair your home's physical structure after a covered loss like fire, wind, or hail. The key number here isn't your home's market value or what you paid for it. It's the replacement cost, meaning what a contractor would charge to rebuild the same structure from the ground up using current materials and labor rates.
In Hershey, replacement costs have climbed steadily since 2023. Lumber, roofing materials, and skilled labor all cost more than they did three years ago, and claims severity has reached record highs nationally. If your dwelling limit hasn't been reviewed in two or more years, you could be underinsured by 15% to 25%. Ask your agent for a replacement cost estimator, not a quick online calculator, but a tool that accounts for your home's square footage, finishes, and any custom features like a stone facade or slate roof.
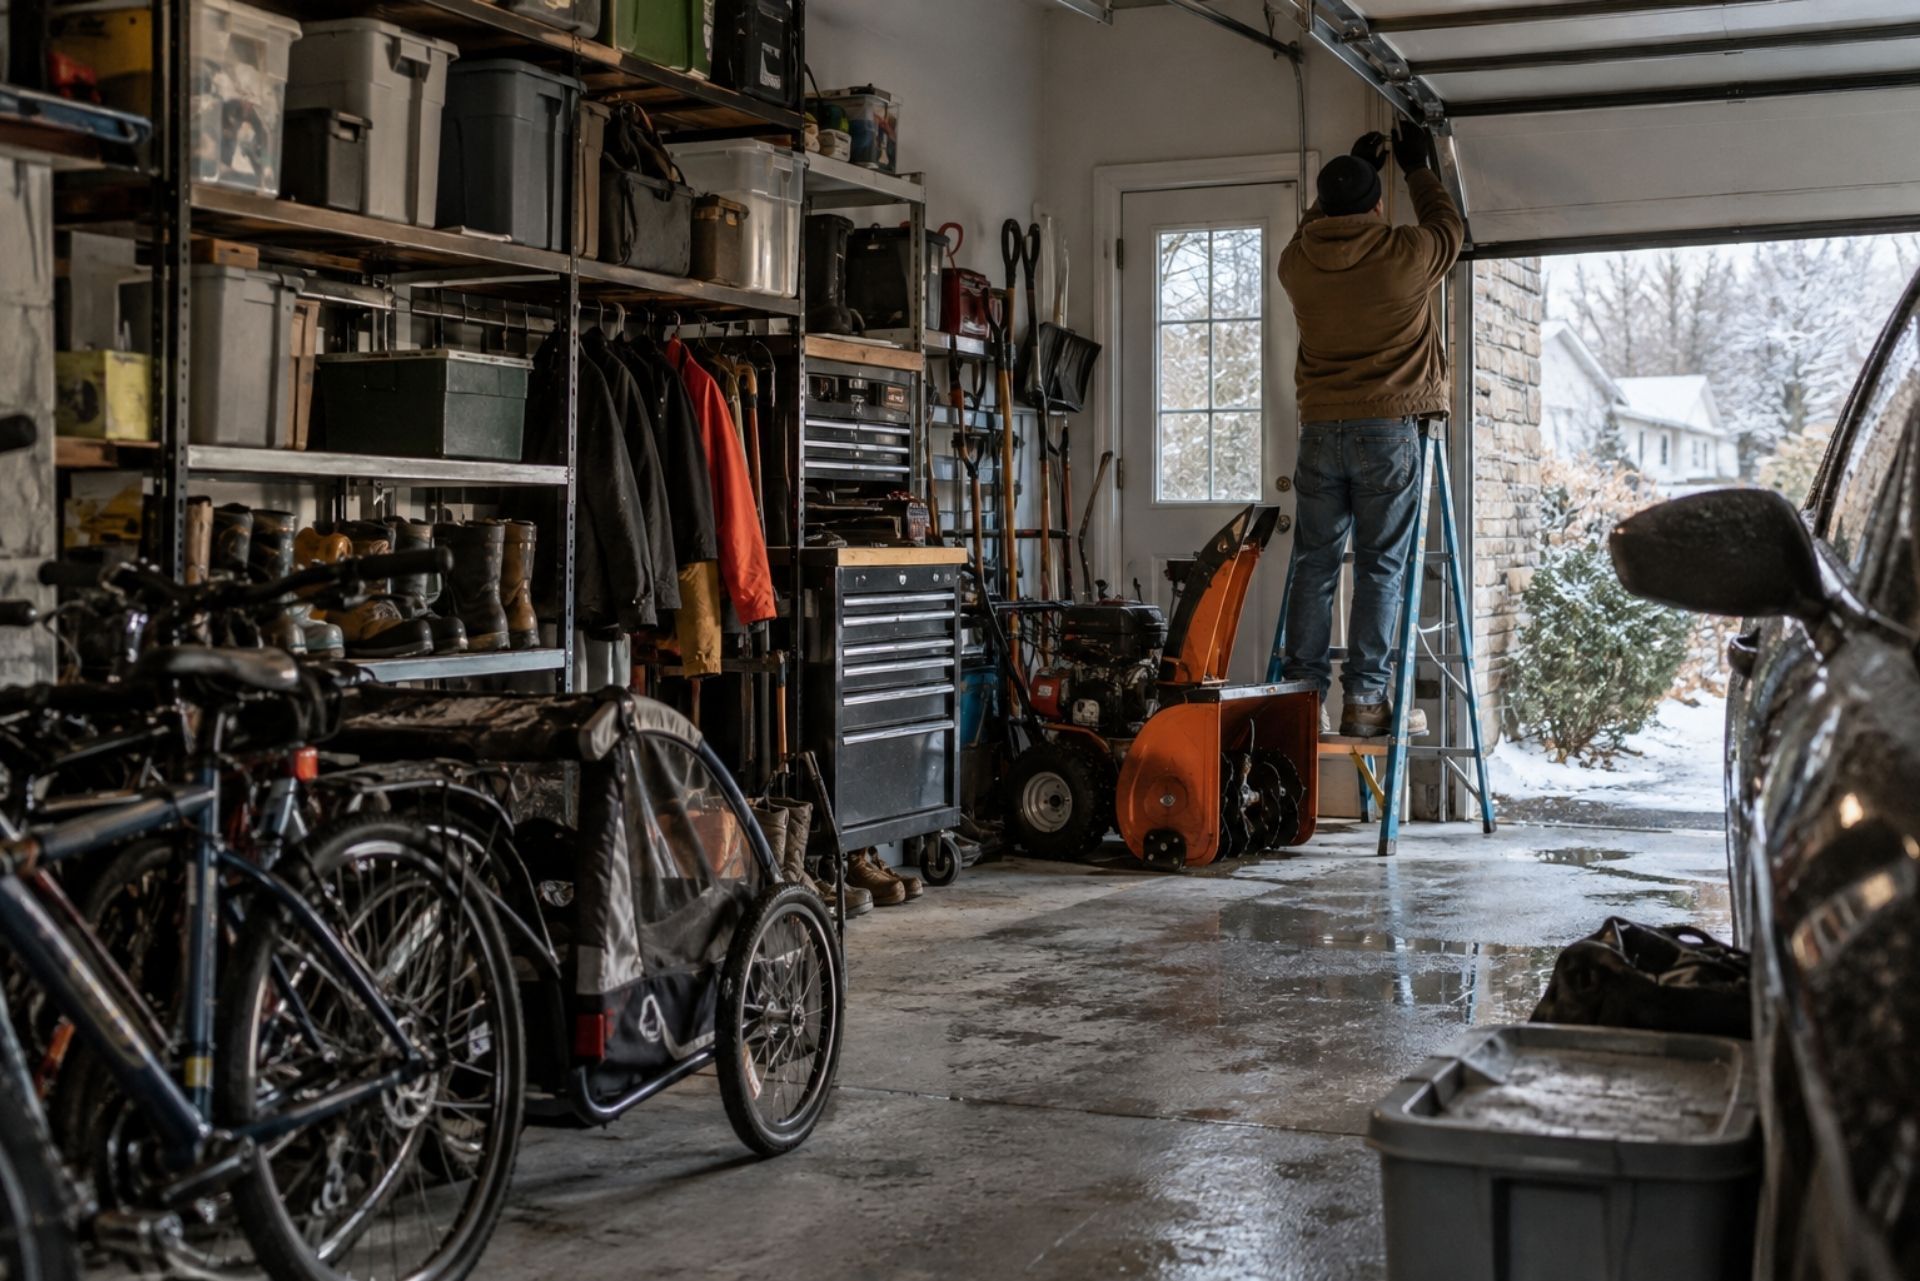
One thing to keep in mind: dwelling coverage typically includes attached structures like a garage or covered porch. Detached structures, such as a shed, fence, or detached garage, fall under a separate "other structures" limit, usually set at 10% of your dwelling amount.
Protecting Your Belongings Anywhere in Hershey
Personal property coverage handles your furniture, clothing, electronics, appliances, and everything else you own inside (and sometimes outside) the home. Standard policies cover belongings at actual cash value, which means the insurer deducts depreciation. A five-year-old laptop that cost $1,200 might only pay out $300.
Replacement cost coverage for personal property costs a bit more per year but pays what it actually takes to buy a comparable new item. For most Hershey homeowners, this upgrade is worth it. The difference between a $300 payout and a $1,200 replacement adds up fast when you're restocking an entire room after a fire or burst pipe.
Your personal property limit is typically 50% to 70% of your dwelling coverage. If your dwelling is insured for $300,000, you'd have $150,000 to $210,000 for belongings. That sounds like plenty until you actually inventory a household. Walk through your home room by room and tally what you own. Most people are surprised to find they're closer to the limit than expected.
Liability and Specialized Water Damage Risks
Structural and property coverage protect your stuff. Liability and water damage endorsements protect your finances from the claims that blindside homeowners most often.
Personal Liability and Medical Payments
If someone slips on your icy front steps or your dog bites a neighbor's child, your liability coverage pays for their medical bills, legal defense costs, and any settlement or judgment. Standard policies include $100,000 in liability, but that's thin protection for a serious injury claim. Most insurance professionals recommend at least $300,000, and an umbrella policy on top of that if your assets exceed your liability limit.
Medical payments coverage is a smaller, no-fault benefit, typically $1,000 to $5,000, that covers minor injuries to guests regardless of who's at fault. It's designed to handle small claims before they become lawsuits. Think of it as goodwill coverage: your neighbor's kid falls off the swing set, and you can help cover the urgent care bill without a formal claim.
Sewer Backup vs. Flood Insurance
Here's where Hershey homeowners get tripped up most often. Standard policies exclude both flood damage and sewer or drain backup. These are two separate risks that require two separate solutions.
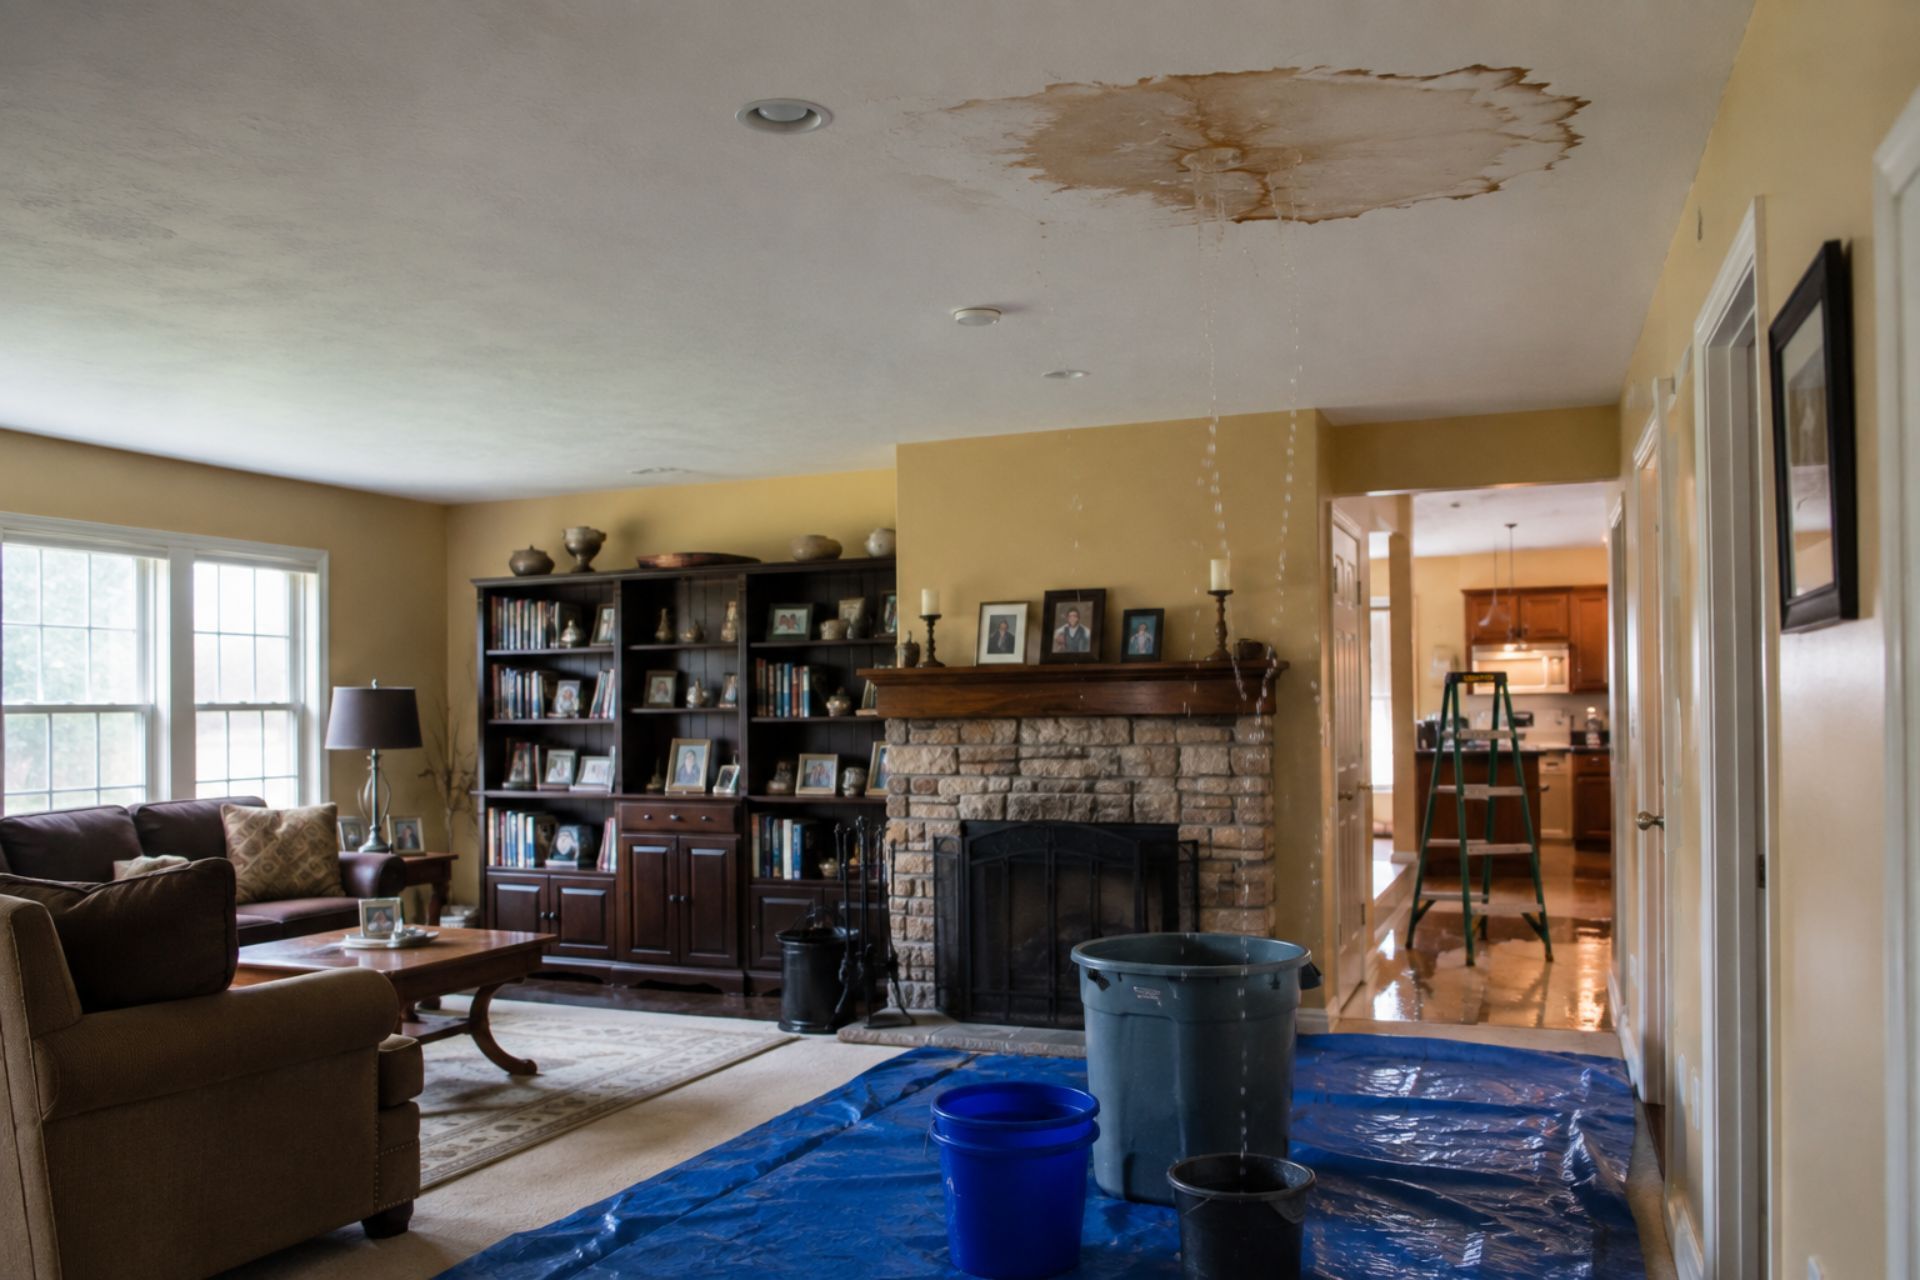
Sewer backup coverage is an endorsement you add to your existing policy, usually for $40 to $75 per year. It covers damage when your home's sewer line backs up or a sump pump fails. Dauphin County's risk profile for water-related claims makes this endorsement essential, not optional. Older neighborhoods in Hershey with clay or cast-iron sewer laterals are especially vulnerable.
Flood insurance is a separate policy, typically through FEMA's National Flood Insurance Program or a private carrier. Even if you're not in a designated flood zone, heavy spring rains and snowmelt can push Spring Creek and its tributaries beyond their banks. If your home sits anywhere near low ground, get a flood quote. The average flood claim in Pennsylvania exceeds $40,000, and none of that is covered by your standard homeowners policy.
Choosing between a basic HO-3 policy and an enhanced package isn't just about price. It's about understanding where each option draws the line on what it will and won't pay.
Table: Standard vs. Enhanced Coverage Limits
| Coverage Component | Standard HO-3 | Enhanced / HO-5 |
|---|---|---|
| Dwelling | Replacement cost | Replacement cost |
| Personal Property | Actual cash value | Replacement cost |
| Personal Property Perils | Named perils only | Open perils (broader) |
| Liability | $100,000 | $300,000+ |
| Water Backup | Not included | Often included |
| Deductible Options | $1,000 - $2,500 | $500 - $2,500 |
| Ordinance or Law | Limited or excluded | Typically 10%-25% of dwelling |
| Identity Theft | Not included | Often included |
The HO-5 costs more, but it shifts the burden of proof. Under an HO-3, your personal property is only covered for specific listed perils like fire, theft, or windstorm. Under an HO-5, everything is covered unless the policy specifically excludes it. That's a meaningful difference when you're dealing with an unusual loss.
How Deductibles Impact Your Monthly Premium
Your deductible is the amount you pay out of pocket before insurance kicks in. Raising it from $1,000 to $2,500 can lower your annual premium by 10% to 20%, but you need to be honest about whether you can absorb that cost after a loss.
A $2,500 deductible makes sense if you have an emergency fund and want to keep premiums low. A $500 deductible makes sense if a sudden $2,500 expense would put you in a tough spot. There's no universally "right" answer here. The best deductible is the one that balances your monthly budget against your ability to handle a surprise bill.
Some Pennsylvania insurers also apply separate wind or hail deductibles, calculated as a percentage of your dwelling limit rather than a flat dollar amount. On a $350,000 home with a 2% wind/hail deductible, you'd owe $7,000 before coverage applies. Ask your agent whether your policy uses
flat or percentage-based deductibles for weather-related claims.
Maximizing Discounts for Pennsylvania Homeowners
Insurance discounts won't transform an expensive policy into a cheap one, but stacking several together can trim 15% to 30% off your annual bill. Here are the most common ones available to Hershey homeowners:
- Bundling your home and auto policies with the same carrier typically saves 10% to 20%.
- A monitored security system or smart home devices (water leak sensors, smoke detectors connected to a central station) can earn 5% to 10%.
- Claims-free discounts reward homeowners who haven't filed a claim in three to five years.
- New roof discounts apply if your roof is less than 10 years old, since newer roofs mean fewer weather claims.
- Loyalty discounts kick in after you've been with the same insurer for three or more years.
- Paying your annual premium in full, rather than monthly installments, often saves 5% to 8%.
One discount that's easy to miss: Pennsylvania offers a reduction for homes with updated electrical, plumbing, and HVAC systems. If you've replaced knob-and-tube wiring, galvanized pipes, or an old fuse box, make sure your insurer knows. These upgrades reduce risk, and insurers reward strong risk profiles with better rates.
Common Questions About Hershey Home Insurance
FAQ: What does home insurance actually cover in Hershey?
A standard HO-3 policy covers your dwelling, other structures, personal property, liability, and additional living expenses if your home becomes uninhabitable. It protects against named perils like fire, wind, hail, theft, and vandalism. It does not cover floods, earthquakes, or sewer backups unless you add separate coverage.
FAQ: Will my policy cover damage from a basement flood?
Not automatically. If the water comes from a backed-up sewer line or failed sump pump, you need a sewer backup endorsement. If the water comes from rising groundwater or an overflowing creek, you need a separate flood insurance policy. Neither is included in a standard homeowners policy.
FAQ: How can I lower my insurance bill without losing coverage?
Raise your deductible to $2,000 or $2,500 if you can handle the out-of-pocket cost. Bundle home and auto. Install water leak sensors and a monitored alarm system. Ask about claims-free and new-roof discounts. Shop your policy every two to three years, since Pennsylvania's insurance market shifts frequently enough that staying with one carrier forever isn't always the cheapest option.
FAQ: Do I need extra coverage for expensive jewelry or collectibles?
Yes. Standard policies cap payouts for jewelry, watches, and furs at $1,500 to $2,500 total. If you own pieces worth more than that, you'll need a scheduled personal property endorsement (sometimes called a floater) that lists each item with its appraised value. This endorsement usually has no deductible and covers a wider range of losses, including accidental damage.
Making the Right Choice for Your Property
Your home in Hershey is more than a financial asset. It's where your family lives, and the right insurance policy should reflect that. Start by confirming your dwelling coverage matches today's rebuilding costs, not what you paid five years ago. Add sewer backup coverage, because the endorsement costs less than a single dinner out and protects against one of the most common claims in Dauphin County.
Review your liability limits and consider whether $100,000 is really enough to protect your savings and future income. Stack every discount you qualify for, and don't skip the annual policy review. Construction costs, local risk factors, and your own home improvements all change over time, and your coverage should keep pace.
Talk to a local independent agent who writes policies in the Hershey area. They'll know which carriers price well for your neighborhood, which endorsements matter most for central Pennsylvania homes, and where you can save without creating dangerous gaps. A 30-minute conversation now can save you thousands after a loss.
ABOUT THE AUTHOR:
TYLER REITZ, CIC, CPCU, ARM, AU
As Managing Principal of Bowmans Insurance, I’m passionate about helping businesses and individuals protect what matters most with clarity and confidence. With advanced designations including CIC, CPCU, ARM, and AU, I bring a comprehensive approach to risk management—ensuring every client receives strategic, reliable, and personalized coverage.
Contact Us
Why Work With Us?
Why Choose Bowman Insurance Group for Personal Insurance?

Choice and Transparency
Bowman Insurance Group works for you, not the insurance providers. We offer a wide selection of policies from reputable insurers, giving you options that suit your unique needs. We prioritize clarity and honesty, ensuring you understand each policy’s benefits and limitations.

Your Personal Advocate
Our team is committed to more than policy sales—we’re here to serve as your advocate. We balance your coverage needs with affordability, working to provide you with the best value without compromise. Every decision we support is made with your best interests in mind.

Expert Guidance for Life
Insurance can feel complex, but we’re here to make it simple. With years of experience, our advisors explain policies clearly and keep you informed of relevant changes. You’ll receive consistent support from trusted professionals who understand your needs and are dedicated to helping you make informed choices.
About Bowman's Insurance Group
Over 100 years Delivering Exceptional Service to Our Community
Personal Insurance Coverage in Pennsylvania
Personal Insurance Solutions in Pennsylvania
Home
Insurance
Auto
Insurance
Umbrella
Insurance
Condo
Insurance
Boat
Insurance
Motorcycle Insurance
RV
Insurance
ATV
Insurance
Insurance Client Reviews
Read our
customer reviews

40+
Insurance Partners
98%
Client Retention Rate
100
Years in Business
98%
Satisfaction Rate
Process of Working With A Personal Insurance Agent in Pennsylvania
Step 1: Initial Assessment
Our process begins with a comprehensive review of your personal insurance needs. We’ll assess factors like your lifestyle, family needs, and assets, so you get the coverage that best suits your unique situation.
Step 2: Customized Consultation
Meet with our knowledgeable agents one-on-one to discuss options tailored to your requirements. We aim to clarify your choices and recommend the most suitable coverage, considering both quality and affordability.
Step 3: Policy Selection & Activation
Once we identify the right coverage, we’ll handle the paperwork and activate your policy. Our team ensures a smooth, straightforward process, giving you confidence and peace of mind in your coverage.
Our Experts
Meet Our Team of Professional Insurance Experts
Tyler Reitz CIC, CPCU, ARM, AU
President
Carmen Donachy, CISR
Treasurer and Customer Service Rep
Brian Brassell, CSA, CRPC
Investment Advisor Representative, Director of Financial Services Division
Kassie Swope, CIC, CISR, AINS
Commercial Department Manager
Our News & Blogs
Latest insurance news & blogs