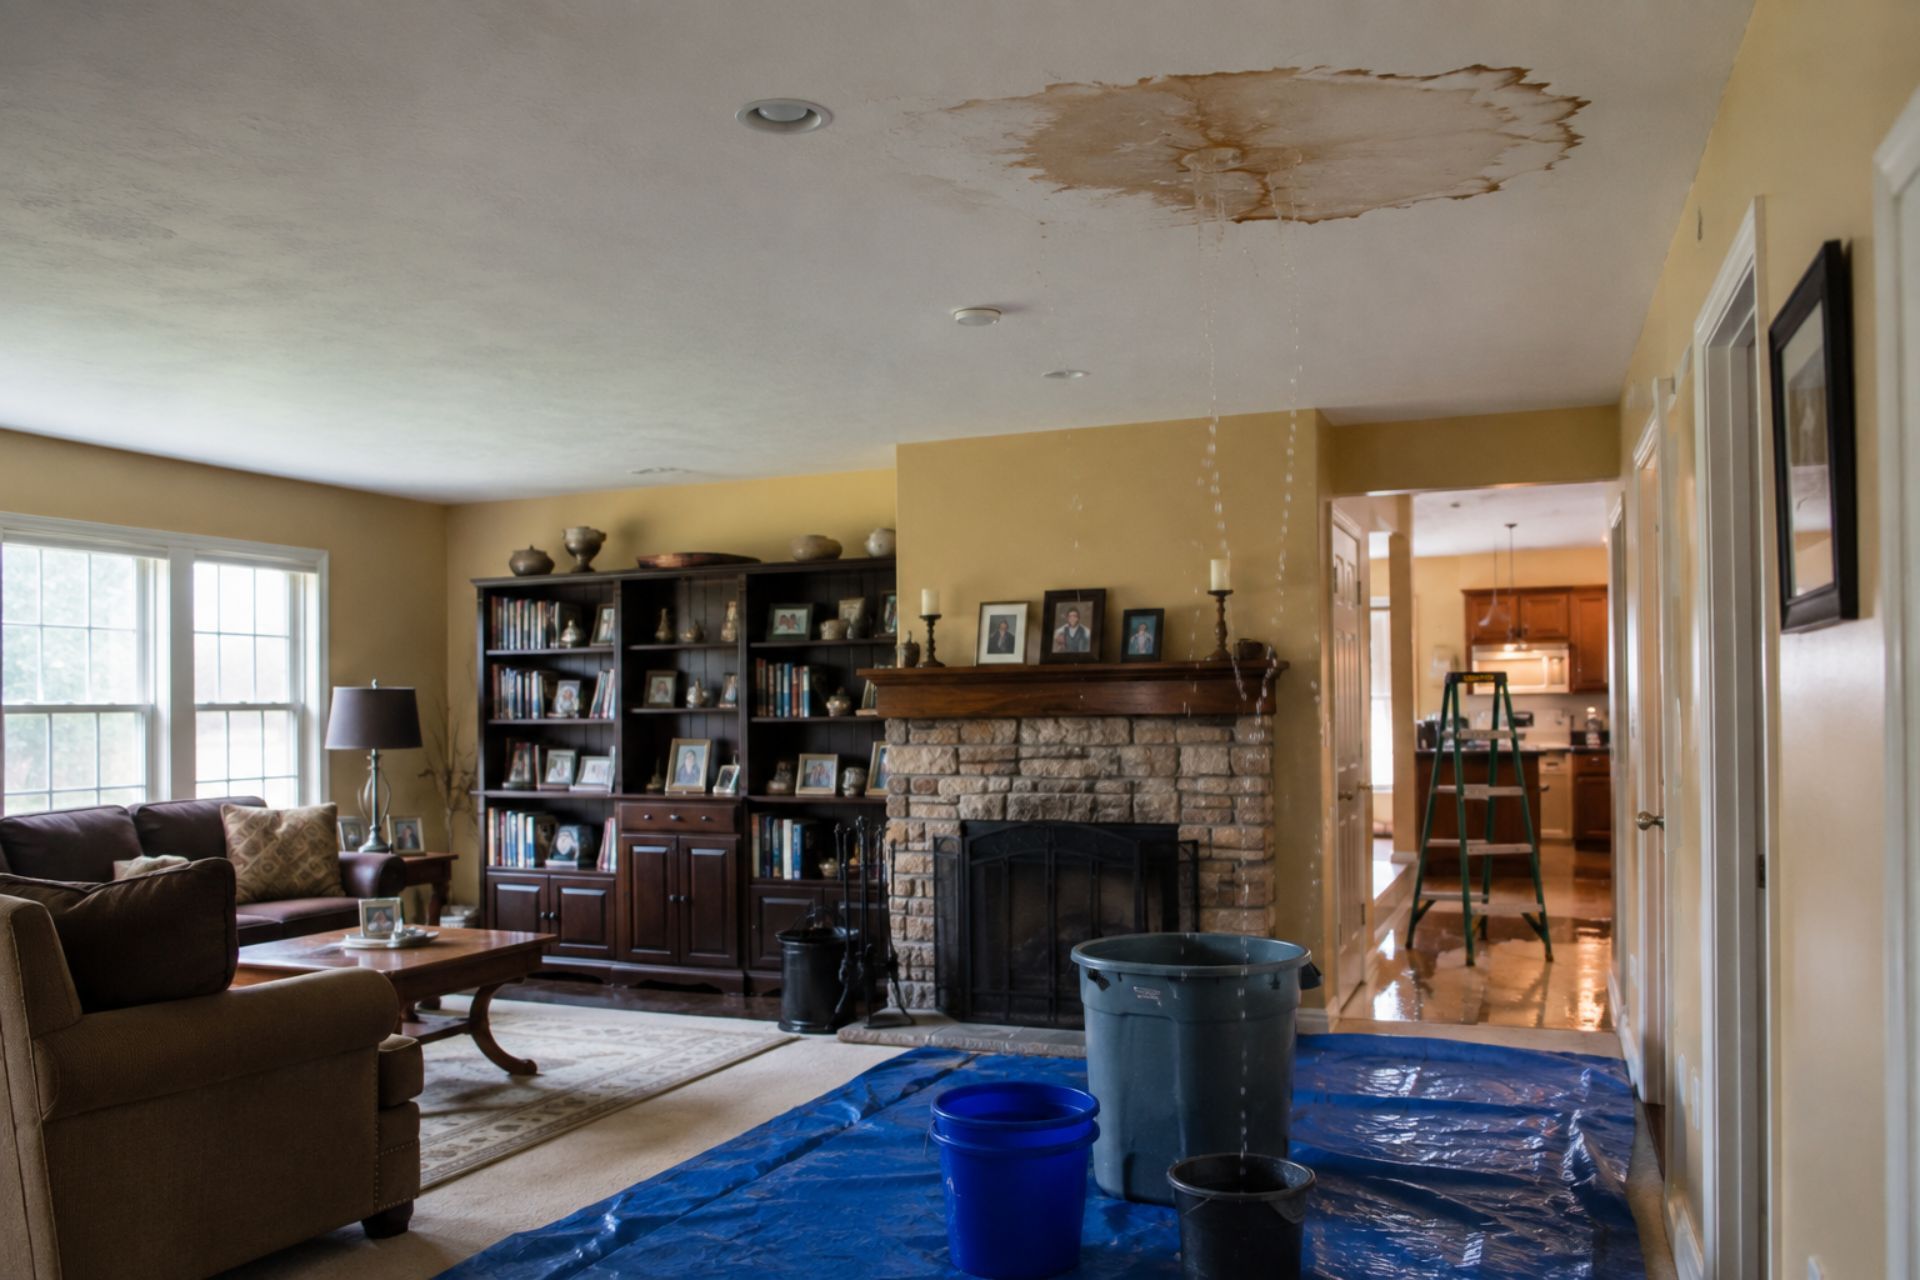

A York County machine shop owner found out the hard way that a single slip-and-fall claim can cost more than a year's rent. The customer tripped over a floor mat in the lobby, fractured a wrist, and filed a lawsuit. Without general liability coverage, that bill would have come straight from the business checking account.
If you run a business in York, PA, you're operating in a market shaped by Pennsylvania-specific regulations, local industry risks, and a commercial insurance climate that's shifting in buyers' favor heading into late 2026. Whether you're covering a retail storefront on Market Street, a fleet of delivery vans, or a growing tech consultancy, the right mix of general liability, property, commercial auto, workers' compensation, and cyber coverage can mean the difference between absorbing a loss and closing your doors. This guide breaks down what each policy does, what it costs, and how to build coverage that actually fits your operation.
Essential Insurance Coverages for York Small Businesses
York's economy blends manufacturing, healthcare, food production, and a growing service sector. Each of these industries carries distinct risks, and no single policy covers them all. Understanding the core coverage types helps you avoid the gaps that lead to out-of-pocket catastrophes.
General Liability and Property Protection
General liability insurance is the foundation for nearly every York business. It covers third-party bodily injury, property damage, and advertising injury claims. If a customer slips in your store, if your employee damages a client's property on a job site, or if you're sued over alleged copyright infringement in an ad campaign, this is the policy that responds.
Commercial property insurance protects your physical assets: your building (if you own it), equipment, inventory, signage, and furniture. For York businesses in older downtown buildings or industrial parks near the Codorus Creek, flood and water damage riders deserve special attention since standard property policies typically exclude flood.
The good news for 2026 is that commercial property rates are trending downward. Increased market capacity and stronger competition among insurers are creating more favorable pricing for businesses, and best-in-class accounts are seeing reductions of 15% to 20% on renewals. If your property policy hasn't been re-quoted recently, now is a smart time to shop.
Pennsylvania Workers' Compensation Requirements
Pennsylvania law requires workers' compensation coverage for almost every employer, including part-time and seasonal workers. There are very few exceptions: sole proprietors with no employees, certain agricultural workers, and some real estate licensees. If you have even one W-2 employee, you need this coverage.
Workers' comp pays for medical treatment, lost wages, and rehabilitation when an employee is injured on the job. It also protects you from lawsuits by injured workers in most circumstances.
Here's a bright spot for York employers: the Pennsylvania Insurance Department approved a 1.22% decrease in workers' compensation loss costs effective April 1, 2026. That reduction flows through to lower premiums for many businesses, especially those with clean claims histories.
Professional Liability for Service Providers
If your York business provides advice, designs, consulting, or any professional service, general liability won't cover claims arising from errors in your work. That's where professional liability, often called errors and omissions (E&O), steps in. An accountant who misfiles a tax return, an IT consultant whose recommendation causes a data breach, or an architect whose design flaw leads to structural problems: these are all E&O claims.
Cyber liability insurance has become closely related to professional liability for many service firms. Business email compromise and funds transfer fraud now
drive 58% of all cyber claims, and these attacks target small businesses as aggressively as large ones. The cyber insurance market currently
favors buyers, with global rates down roughly 6%, though insurers are tightening policy language around social engineering coverage. Read the fine print on verification requirements before you sign.
By: Tyler Reitz
Managing Principal of Bowmans Insurance
Comparing Policy Types: Basic vs. Comprehensive Bundles
Most small business owners in York face a choice: buy individual policies for each risk, or bundle them into a Business Owner's Policy (BOP). A BOP typically combines general liability and commercial property into a single package at a lower premium than buying each separately. Some BOPs also include business interruption coverage, which pays lost income if a covered event forces you to close temporarily.
The trade-off is flexibility. Standalone policies let you customize limits, deductibles, and endorsements for each coverage type. A BOP offers convenience and savings but may cap your limits lower than you'd like for certain exposures.
Comparison Table: Business Owner's Policy (BOP) vs. Standalone Coverage
| Feature | BOP (Bundled) | Standalone Policies |
|---|---|---|
| General Liability | Included | Purchased separately |
| Commercial Property | Included | Purchased separately |
| Business Interruption | Often included | Must add separately |
| Customizable Limits | Limited flexibility | Full control per policy |
| Cost | Lower combined premium | Higher total but tailored |
| Best For | Low-to-moderate risk businesses | Higher-risk or complex operations |
| Add-on Options | Some endorsements available | Unlimited endorsement options |
| Cyber Coverage | Rarely included | Purchased as standalone |
A BOP works well for a York retail shop, small restaurant, or office-based service company. If you're running a manufacturing operation, a construction firm, or a business with a large vehicle fleet, standalone policies give you the room to match coverage to your actual risk profile.
Factors Influencing Insurance Costs in York County
Two businesses on the same block in York can pay dramatically different premiums. Understanding why helps you control costs without cutting corners on coverage.
Industry Risk and Physical Location
Insurance carriers classify businesses by industry codes, and each code carries a risk rating based on historical claims data. A roofing contractor pays far more for general liability than a bookkeeping firm because the likelihood and severity of claims are higher.
Your physical location matters too. A business in a flood-prone area near the Codorus Creek will pay more for property coverage, or may need a separate flood policy entirely. Buildings with outdated electrical or plumbing systems, common in York's older commercial districts, can also trigger higher premiums. Upgrading fire suppression systems, installing security cameras, and maintaining code-compliant wiring are practical steps that often lead to lower rates.
For commercial auto coverage, Pennsylvania recently raised the auto accident surcharge threshold to $2,350 effective July 1, 2026. This means insurers can't increase your premium for claims that fall below that aggregate cap over three years, which is a small but meaningful protection for businesses with delivery vehicles or service fleets.
Payroll Size and Annual Revenue
Workers' compensation premiums are calculated directly from your payroll. The formula multiplies your payroll per $100 by a rate assigned to each employee's job classification. A warehouse worker carries a higher rate than an office administrator. Keeping accurate payroll records and making sure employees are classified correctly can prevent you from overpaying.
Annual revenue also influences general liability and professional liability premiums. Carriers view higher revenue as higher exposure: more customers, more transactions, more potential claims. As your revenue grows, expect your premiums to adjust. The flip side is that a business with strong revenue and a clean claims history often qualifies for better rates than a startup with no track record.
One cost factor many York business owners overlook is their experience modification rate (EMR) for workers' comp. This score compares your claims history to others in your industry. An EMR below 1.0 earns you a discount. Above 1.0, and you're paying a surcharge. Investing in workplace safety programs directly impacts this number over time.
Common Questions About York Business Insurance
FAQ: Do I really need insurance if I work from home in York?
Yes. Your homeowner's policy almost certainly excludes business activities. If a client visits your home office and gets injured, or if business equipment is stolen, your homeowner's insurer will likely deny the claim. A small BOP or in-home business endorsement fills that gap affordably.
FAQ: How much does a basic policy cost for a new startup?
Costs vary widely by industry and coverage needs. A BOP for a small retail operation typically runs higher but bundles more protection. The best approach is to get quotes from at least three carriers with your specific revenue, payroll, and industry details.
FAQ: Is workers' comp mandatory if I only have one employee?
In Pennsylvania, yes. The state requires workers' compensation coverage for nearly all employers, regardless of how many employees you have. Sole proprietors and certain partners can exempt themselves, but your employees must be covered. Penalties for non-compliance include fines and potential criminal charges.
FAQ: Can I change my coverage as my business grows?
You can and should. Most policies allow mid-term endorsements to add coverage, increase limits, or add new locations and vehicles. Review your coverage at least annually, and notify your agent whenever you hire employees, purchase equipment, sign a lease, or add a service line. Gaps tend to form when businesses grow faster than their policies.
FAQ: What information do I need to get an accurate quote?
Come prepared with your business entity type, EIN, industry description, annual revenue, payroll breakdown by job classification, property values, vehicle list (for commercial auto), and any prior claims history. The more precise your information, the more accurate your quote. Vague estimates lead to policies that are either overpriced or dangerously underinsured.
Making the Right Choice for Your Local Company
Getting business insurance in York right means matching your coverage to the risks you actually face, not buying the cheapest option and hoping for the best. A restaurant on West Market Street has different needs than a trucking company off Route 30 or a cybersecurity consultancy working remotely from Springettsbury Township.
Start with the coverages Pennsylvania requires: workers' compensation if you have employees, and commercial auto if you operate vehicles. Build from there with general liability, property, and any specialty coverage your industry demands. Take advantage of the current buyer-friendly market for property and cyber policies, and don't skip the annual policy review.
The smartest York business owners treat insurance as a risk management tool, not just a line item. Talk to an independent agent who understands York County's market, get multiple quotes, and ask hard questions about exclusions and sublimits. Your future self, the one who doesn't have to write a six-figure check after an unexpected claim, will thank you.
ABOUT THE AUTHOR:
TYLER REITZ, CIC, CPCU, ARM, AU
As Managing Principal of Bowmans Insurance, I’m passionate about helping businesses and individuals protect what matters most with clarity and confidence. With advanced designations including CIC, CPCU, ARM, and AU, I bring a comprehensive approach to risk management—ensuring every client receives strategic, reliable, and personalized coverage.
Contact Us
Why Work With Us?
Why Choose Bowman Insurance Group for Personal Insurance?

Choice and Transparency
Bowman Insurance Group works for you, not the insurance providers. We offer a wide selection of policies from reputable insurers, giving you options that suit your unique needs. We prioritize clarity and honesty, ensuring you understand each policy’s benefits and limitations.

Your Personal Advocate
Our team is committed to more than policy sales—we’re here to serve as your advocate. We balance your coverage needs with affordability, working to provide you with the best value without compromise. Every decision we support is made with your best interests in mind.

Expert Guidance for Life
Insurance can feel complex, but we’re here to make it simple. With years of experience, our advisors explain policies clearly and keep you informed of relevant changes. You’ll receive consistent support from trusted professionals who understand your needs and are dedicated to helping you make informed choices.
About Bowman's Insurance Group
Over 100 years Delivering Exceptional Service to Our Community
Personal Insurance Coverage in Pennsylvania
Personal Insurance Solutions in Pennsylvania
Home
Insurance
Auto
Insurance
Umbrella
Insurance
Condo
Insurance
Boat
Insurance
Motorcycle Insurance
RV
Insurance
ATV
Insurance
Insurance Client Reviews
Read our
customer reviews

40+
Insurance Partners
98%
Client Retention Rate
100
Years in Business
98%
Satisfaction Rate
Process of Working With A Personal Insurance Agent in Pennsylvania
Step 1: Initial Assessment
Our process begins with a comprehensive review of your personal insurance needs. We’ll assess factors like your lifestyle, family needs, and assets, so you get the coverage that best suits your unique situation.
Step 2: Customized Consultation
Meet with our knowledgeable agents one-on-one to discuss options tailored to your requirements. We aim to clarify your choices and recommend the most suitable coverage, considering both quality and affordability.
Step 3: Policy Selection & Activation
Once we identify the right coverage, we’ll handle the paperwork and activate your policy. Our team ensures a smooth, straightforward process, giving you confidence and peace of mind in your coverage.
Our Experts
Meet Our Team of Professional Insurance Experts
Tyler Reitz CIC, CPCU, ARM, AU
President
Carmen Donachy, CISR
Treasurer and Customer Service Rep
Brian Brassell, CSA, CRPC
Investment Advisor Representative, Director of Financial Services Division
Kassie Swope, CIC, CISR, AINS
Commercial Department Manager
Our News & Blogs
Latest insurance news & blogs