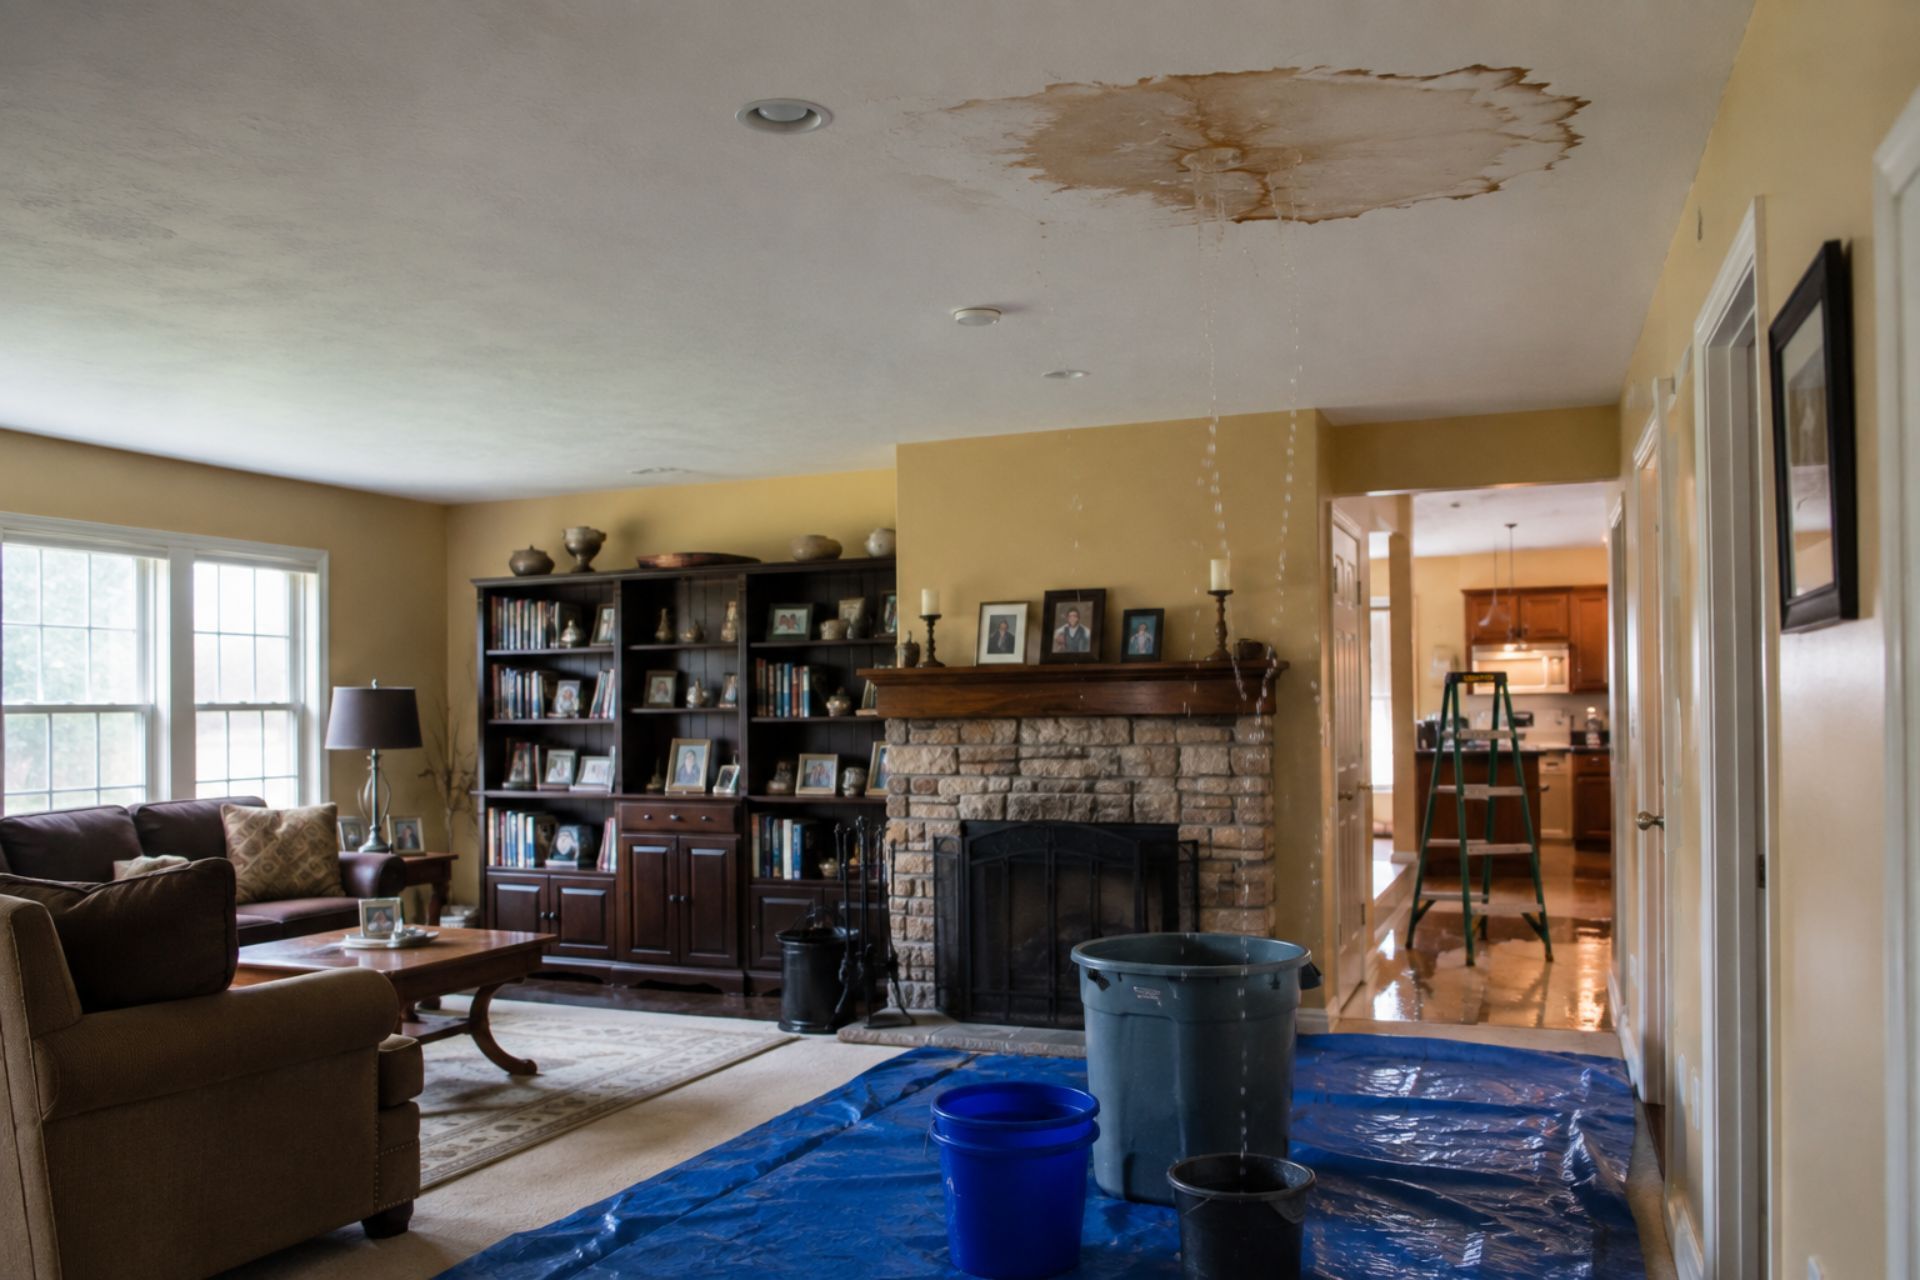

Picture a Penn Street café owner in downtown Reading who slips through a full year without a claim, then gets hit with three problems in one month. A customer falls on a wet floor near the entrance. A delivery driver backs the company van into a parked car on Lancaster Avenue. A phishing email locks up the point-of-sale system right before the weekend rush. Each event lands on a different policy, and any one of them could cost more than the café clears in a year.
This is the reality of running a business in Berks County. The risks don't arrive one at a time, and they don't care how careful you are. What matters is whether your coverage was built for the way your company actually operates, or pieced together from whatever a carrier offered first.
This guide to business insurance in Reading, PA covers general liability, property, commercial auto, workers' compensation, cyber, and costs. It's written for owners who want straight answers: what's required, what's optional but smart, and what drives your premium up or down. You'll also find common mistakes we see Reading businesses make, plus a quick FAQ for the questions owners ask most often before buying or renewing a policy.
Protecting Your Business in the Reading Market
Reading isn't Philadelphia, and your insurance shouldn't be priced or structured like it is. The city has a dense mix of older commercial buildings, family-owned manufacturers, contractors serving the wider Berks County area, healthcare offices, and a growing number of restaurants and retail shops. Each of those business types carries a different risk profile.
Local conditions shape your coverage needs too. Older brick buildings downtown often have outdated electrical or plumbing systems, which affects property underwriting. Contractors working across Berks, Lancaster, and Lehigh counties put more miles on their vehicles. And the City of Reading's 2026 budget raised property taxes by about 9%, pushing the millage rate to roughly 19.761 mils. That squeezes margins, which makes it tempting to cut insurance spending.
Don't. The catch is that
underinsurance usually reveals itself at the worst possible moment, during a claim. Before you shop on price alone, confirm your basic local obligations are handled. Reading's
Business Privilege License fee is $55 for 2026, and landlords and commercial clients will often ask for proof of insurance before you sign a lease or contract.
By: Tyler Reitz
Managing Principal of Bowmans Insurance
Core Coverage: General Liability and Property Protection
Most Reading businesses start with two policies: general liability and commercial property. Together, they cover the most common losses a small business faces.
General liability pays for third-party bodily injury, property damage, and certain advertising injuries. That café slip-and-fall is a textbook GL claim. So is a plumber who cracks a customer's tile floor while installing a fixture.
Commercial property covers your building (if you own it), equipment, inventory, furniture, and improvements you've made to a leased space. Here's where owners trip up:
- Valuation method: Replacement cost pays to replace items new. Actual cash value subtracts depreciation, which can leave you thousands short.
- Tenant improvements: If you built out a leased storefront, your landlord's policy probably doesn't cover your upgrades.
- Business income: This pays lost revenue and ongoing expenses while you're closed after a covered loss. Many owners skip it and regret it.
- Flood exclusion: Standard property policies exclude flood. Businesses near the Schuylkill River should ask about separate flood coverage.
Many small businesses bundle both into a business owner's policy (BOP), which is often cheaper than buying each separately.
General Liability vs. Professional Liability
Most owners don't realize general liability won't cover mistakes in the advice or services they provide. That's what professional liability, also called an E&O policy, is for.
| Factor | General Liability | Professional Liability (E&O) |
|---|---|---|
| Covers | Physical injury and property damage | Financial loss from errors or negligence |
| Example | Client trips over a cord in your office | Accountant's filing error triggers IRS penalties |
| Who needs it | Nearly every business | Consultants, accountants, IT firms, architects, agents |
| Typical trigger | Accident | Alleged mistake or missed deadline |
An IT consultant in Wyomissing who misconfigures a client's backup system won't find help in a GL policy. That's an E&O claim, and those can turn into six-figure settlements.
Pennsylvania Requirements for Workers' Comp and Commercial Auto
Pennsylvania takes workers' compensation seriously. Almost every employer with even one employee, full-time or part-time, must carry it. There's no small-business exemption based on headcount, which surprises owners moving here from other states.
The penalties for going without are severe. Failing to carry required workers' comp in Pennsylvania can bring criminal charges, not just fines, and you'd be personally on the hook for an injured worker's medical bills and lost wages.
Benefit levels also climb each year. For injuries on or after January 1, 2026, the Statewide Average Weekly Wage is set at $1,394.00, and that figure sets the cap on wage-loss benefits. Here's what that means for you: as maximum benefits rise, so does the potential cost of a serious claim, and carriers price that into premiums.
Commercial auto works differently. Any vehicle titled to your business needs commercial coverage, and Pennsylvania's minimum liability limits apply. One thing to keep in mind: your personal auto policy likely excludes business use. If your HVAC tech drives his own truck to a job and causes an accident, his personal carrier may deny the claim. Hired and non-owned auto coverage fills that gap.
Comparing State Mandates vs. Optional Limits
| Coverage | Required in PA? | Smart Practice |
|---|---|---|
| Workers' comp | Yes, for nearly all employers | Classify employees correctly to avoid audit surprises |
| Commercial auto liability | Yes, at state minimums for business-owned vehicles | Carry limits well above minimums |
| Hired/non-owned auto | No | Essential if employees drive personal cars for work |
| General liability | No, but often contract-required | Match limits to lease and client contracts |
State minimum auto limits are a floor, not a recommendation. A single multi-vehicle accident on Route 422 can blow past them fast.
Addressing Modern Risks with Cyber Insurance
A Reading dental practice doesn't think of itself as a tech company. Then ransomware encrypts its patient records, and suddenly it's dealing with forensic investigators, breach notification laws, and patients demanding answers.
Cyber insurance covers costs that general liability and property policies typically exclude. A solid policy usually includes:
- Breach response: Forensics, legal counsel, and notifying affected customers
- Ransomware and extortion: Negotiation help and, in some cases, payment
- Business interruption: Lost income while systems are down
- Third-party liability: Lawsuits from customers whose data was exposed
- Funds transfer fraud: Money wired to criminals after a fake invoice or spoofed email
That last item causes plenty of headaches. A common scenario: a bookkeeper gets an email that looks like it's from a regular supplier, with new wiring instructions. They send $40,000. Many cyber policies limit or exclude this "social engineering" loss unless you add a specific endorsement.
Underwriters now ask detailed questions before quoting. Expect them to check for multi-factor authentication, offline backups, and employee training. Businesses with stronger controls get better rates, and in some cases, weak controls mean you won't get coverage at all.
What Determines Business Insurance Costs in Berks County?
No honest agent can quote you a number without knowing your business. Premiums for business insurance in the Reading area depend on a handful of factors that underwriters weigh differently for each policy.
The biggest drivers include:
- Industry and class code: A roofing contractor pays far more for workers' comp than an accounting office
- Payroll: Workers' comp premiums are calculated per $100 of payroll by job classification
- Revenue: Often the rating basis for general liability
- Claims history: Prior losses follow you for years
- Building age and construction: Older downtown properties with outdated systems cost more to insure
- Driving records: One employee with multiple violations can raise your whole commercial auto premium
- Coverage limits and deductibles: Higher deductibles lower premiums, but only if you can absorb the out-of-pocket hit
That said, you have more control than you think. Written safety programs, return-to-work policies, and driver screening all signal lower risk. Strong internal controls, like dual authorization for wire transfers, can improve cyber terms. Insurers reward oversight they can verify.
Cost Breakdown by Industry Type
Rather than inventing averages, here's where the money typically goes for common Reading businesses:
| Industry | Largest Cost Driver | Watch For |
|---|---|---|
| Contractors (HVAC, plumbing, roofing) | Workers' comp and GL | Subcontractor certificates |
| Restaurants | Property and GL | Liquor liability if serving alcohol |
| Manufacturers | Workers' comp and property | Equipment breakdown |
| Professional offices | E&O and cyber | Client data exposure |
| Retail | Property and GL | Inventory valuation |
Contractors often get hit at their workers' comp audit when uninsured subcontractors get added to their payroll. Collect certificates of insurance from every sub, every time.
Common Questions About Reading Business Insurance
Do I need business insurance if I work from home in Reading? Probably. Homeowners policies usually exclude business equipment and client injuries, so a home-based business policy or BOP closes that gap.
Is workers' comp required if I only have one part-time employee? Yes. Pennsylvania requires coverage for nearly all employers, regardless of hours worked.
Can I use my personal truck for my business? You can, but your personal auto policy may deny claims tied to business use. Ask about commercial auto or hired and non-owned coverage.
Does general liability cover cyberattacks? Generally no. Data breaches and ransomware need a separate cyber policy.
What's a certificate of insurance, and why do clients ask for it? It's a one-page document proving your coverage and limits. Landlords and general contractors use it to confirm you can pay for damage you cause.
How often should I review my coverage?
At least once a year, and any time you hire, buy equipment, add vehicles, or sign a major contract.
Making the Right Choice for Your Company
Reading businesses face a specific mix of pressures in 2026: rising local property taxes, higher workers' comp benefit caps, older commercial buildings, and cyber threats that don't care how small you are. The right insurance setup accounts for all of it without paying for coverage you'll never use.
Start with the essentials Pennsylvania requires, workers' comp and commercial auto for business vehicles. Layer in general liability and property, then decide honestly whether your business handles client data or gives professional advice. If it does, cyber and E&O aren't optional extras.
Your next steps are simple. Gather your payroll figures, vehicle list, revenue, and any lease or client contracts with insurance requirements. Then sit down with an independent agent who knows Berks County and can compare multiple carriers. The cheapest quote rarely wins at claim time. The policy built for your actual operations does.
ABOUT THE AUTHOR:
TYLER REITZ, CIC, CPCU, ARM, AU
As Managing Principal of Bowmans Insurance, I’m passionate about helping businesses and individuals protect what matters most with clarity and confidence. With advanced designations including CIC, CPCU, ARM, and AU, I bring a comprehensive approach to risk management—ensuring every client receives strategic, reliable, and personalized coverage.
Contact Us
Why Work With Us?
Why Choose Bowman Insurance Group for Personal Insurance?

Choice and Transparency
Bowman Insurance Group works for you, not the insurance providers. We offer a wide selection of policies from reputable insurers, giving you options that suit your unique needs. We prioritize clarity and honesty, ensuring you understand each policy’s benefits and limitations.

Your Personal Advocate
Our team is committed to more than policy sales—we’re here to serve as your advocate. We balance your coverage needs with affordability, working to provide you with the best value without compromise. Every decision we support is made with your best interests in mind.

Expert Guidance for Life
Insurance can feel complex, but we’re here to make it simple. With years of experience, our advisors explain policies clearly and keep you informed of relevant changes. You’ll receive consistent support from trusted professionals who understand your needs and are dedicated to helping you make informed choices.
About Bowman's Insurance Group
Over 100 years Delivering Exceptional Service to Our Community
Personal Insurance Coverage in Pennsylvania
Personal Insurance Solutions in Pennsylvania
Home
Insurance
Auto
Insurance
Umbrella
Insurance
Condo
Insurance
Boat
Insurance
Motorcycle Insurance
RV
Insurance
ATV
Insurance
Insurance Client Reviews
Read our
customer reviews

40+
Insurance Partners
98%
Client Retention Rate
100
Years in Business
98%
Satisfaction Rate
Process of Working With A Personal Insurance Agent in Pennsylvania
Step 1: Initial Assessment
Our process begins with a comprehensive review of your personal insurance needs. We’ll assess factors like your lifestyle, family needs, and assets, so you get the coverage that best suits your unique situation.
Step 2: Customized Consultation
Meet with our knowledgeable agents one-on-one to discuss options tailored to your requirements. We aim to clarify your choices and recommend the most suitable coverage, considering both quality and affordability.
Step 3: Policy Selection & Activation
Once we identify the right coverage, we’ll handle the paperwork and activate your policy. Our team ensures a smooth, straightforward process, giving you confidence and peace of mind in your coverage.
Our Experts
Meet Our Team of Professional Insurance Experts
Tyler Reitz CIC, CPCU, ARM, AU
President
Carmen Donachy, CISR
Treasurer and Customer Service Rep
Brian Brassell, CSA, CRPC
Investment Advisor Representative, Director of Financial Services Division
Kassie Swope, CIC, CISR, AINS
Commercial Department Manager
Our News & Blogs
Latest insurance news & blogs