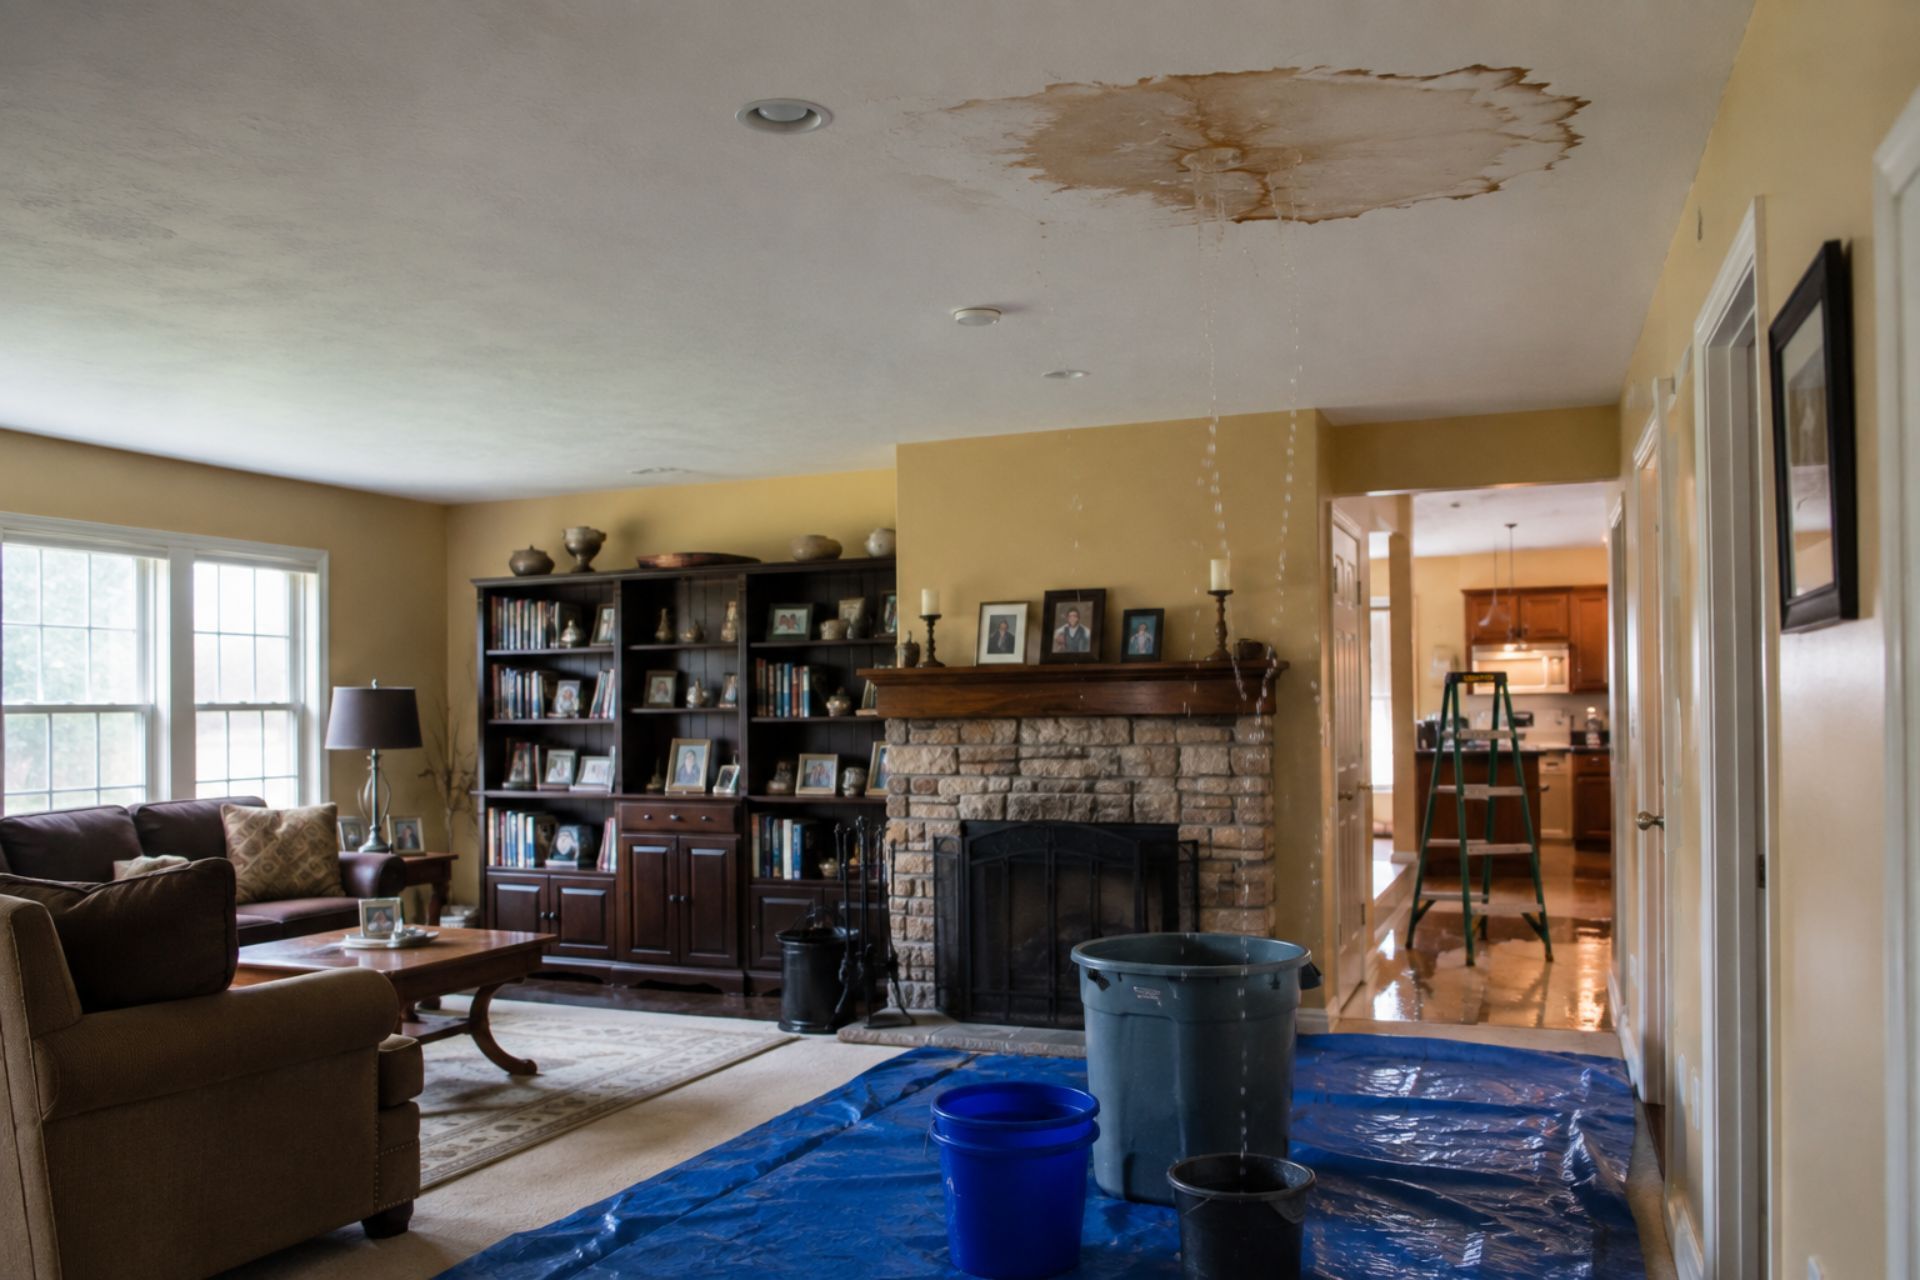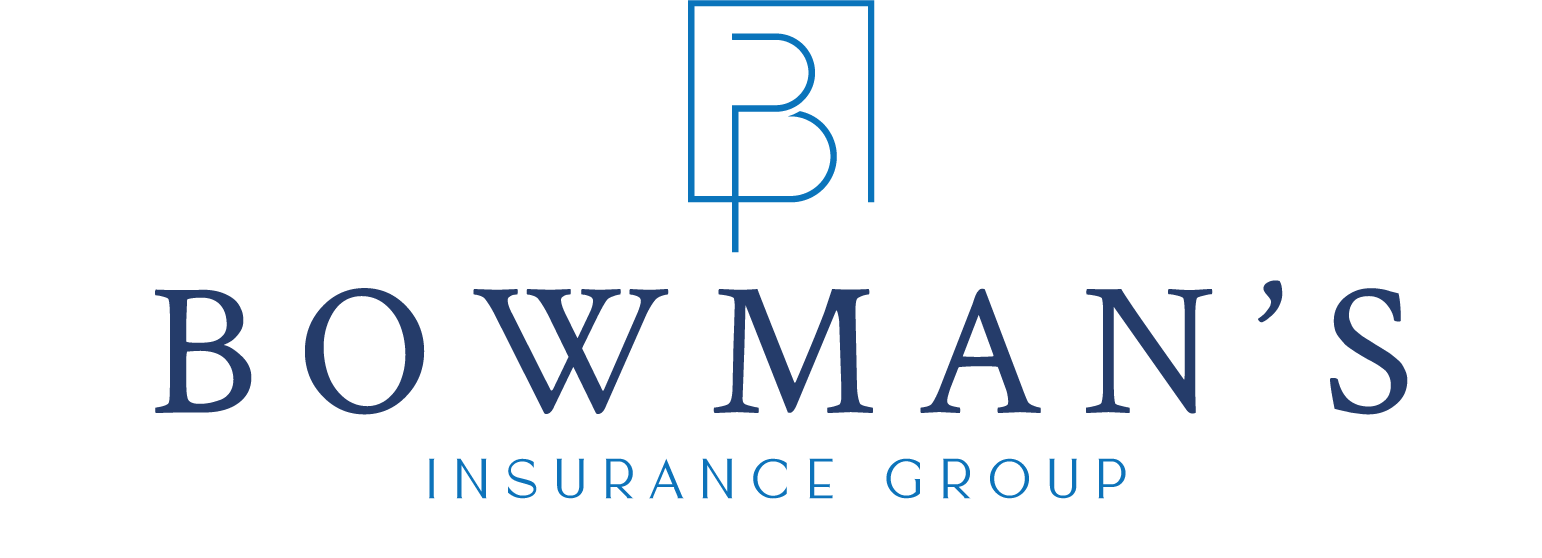

A burst supply line under a Midtown rowhouse sink can soak hardwood floors, warp cabinets, and drip into the neighbor's ceiling before anyone wakes up. A single overnight leak like that can turn into a five-figure repair bill. Whether your policy pays depends on details most people never read until they file a claim.
Harrisburg homeowners also face local risks that a generic policy doesn't always address. The Susquehanna River sits right at the city's edge, and older housing stock is common in neighborhoods like Shipoke and Allison Hill. Parts of the region also carry abandoned mine risk underground.
Good home insurance in Harrisburg, PA starts with knowing what each part of your policy does, where the gaps are, and how to lower your premium without stripping out protection you'll need later.
Understanding Home Insurance Essentials in Harrisburg
Cost is the first thing most buyers ask about. Harrisburg homeowners pay an average annual premium between $1,600 and $1,850 as of August 2026. That's less than Philadelphia but more than Lancaster. Your actual rate depends on your home's age, roof condition, claims history, and the coverage limits you choose.
A standard homeowners policy (usually an HO-3) bundles several protections together. The state's homeowners insurance consumer guide breaks these into separate coverage parts, each with its own limit. The three that matter most are covered below.
Dwelling Coverage and Personal Property Protection
Dwelling coverage pays to repair or rebuild the structure itself: walls, roof, built-in HVAC, plumbing, and attached garages. The limit should match your rebuild cost, not your market value or purchase price. That's a common mistake in Harrisburg, where a $220,000 brick rowhouse might cost $300,000 or more to rebuild with matching plaster and masonry.
Personal property coverage protects your belongings, from furniture to electronics. Pay attention to how losses are valued:
- Actual cash value (ACV): pays what the item is worth today, after depreciation
- Replacement cost: pays what it costs to buy a new equivalent
A five-year-old laptop might bring $200 under ACV and $1,100 under replacement cost. That gap adds up fast across a whole household.
Liability Insurance for PA Homeowners
Liability coverage pays legal costs and damages if someone gets hurt on your property or you accidentally damage someone else's. Think of a delivery driver slipping on an icy Front Street stoop, or that leak from your unit ruining the condo below.
Many policies default to $100,000 in liability. Most agents recommend at least $300,000, and a personal umbrella policy is cheap protection if you have significant assets. Six-figure injury settlements aren't rare, and anything above your limit comes out of your pocket.
By: Tyler Reitz
Managing Principal of Bowmans Insurance
Addressing Harrisburg Risks: Water Damage and Deductibles
Water claims are where most Harrisburg homeowners get surprised. Standard policies generally cover sudden, accidental water damage, like a burst pipe in January. They usually exclude gradual leaks, long-term seepage, and flooding.
Your deductible shapes every claim too. Raising it from $500 to $1,000 or $2,500 lowers your premium, but only choose a number you could pay tomorrow without stress. Some carriers also apply separate wind or water deductibles, so read the declarations page closely.
Don't overlook the ground under your house. Over 1 million Pennsylvania homes sit above abandoned mines, and standard policies exclude earth movement. The DEP offers Mine Subsidence Insurance for roughly $1 per $1,000 of coverage, which is worth checking if you live in a mining-affected area of the region.
Flood vs. Water Backup Coverage
These two get confused constantly, and the difference can cost you tens of thousands.
| Coverage | What It Covers | Included in Standard Policy? |
|---|---|---|
| Flood insurance | Rising water from rivers, heavy rain, storm surge | No, separate policy |
| Water backup endorsement | Sewer or drain backups, sump pump failure | No, add-on rider |
| Sudden water damage | Burst pipes, appliance overflow | Usually yes |
State regulators put it bluntly: "where it rains, it can flood," and they urge even low-risk homeowners to consider flood coverage. As of October 23, 2026, House Bill 1704 also requires sellers to give enhanced disclosures about a property's flood history and risk. If you're buying, read those disclosures carefully.
Ways to Save on Your Pennsylvania Policy
Lower premiums usually come from a mix of small moves rather than one big fix. Here's where Harrisburg homeowners find real savings:
- Bundle home and auto. Pennsylvania drivers typically save between 10% and 22% by combining policies, with some carriers at the top of that range.
- Use Harrisburg's flood rating. Because of the city's Level 6 Community Rating System status, residents get a 20% flood insurance discount in the 100-year floodplain and 10% in the 500-year floodplain.
- Install protective devices. Monitored alarms, smart water shutoff valves, and leak sensors often qualify for discounts.
- Update older systems. A new roof or replacement of outdated wiring can lower your rate and make you easier to insure.
- Raise your deductible if you have solid emergency savings.
One thing to keep in mind: the cheapest quote often comes with ACV roof coverage or low liability limits. Compare policies line by line, not just the premium.
Common Questions About Harrisburg Home Insurance
Does homeowners insurance cover flooding from the Susquehanna? No. River flooding requires a separate flood policy through the NFIP or a private insurer.
How much dwelling coverage do I need? Enough to rebuild your home at today's labor and material costs. Ask your agent for a replacement cost estimate instead of relying on your sale price.
Is mine subsidence covered? Not under a standard policy. You'd need the state's Mine Subsidence Insurance program.
What's a good deductible for most homeowners? Many people choose $1,000. Go higher only if you can comfortably cover that amount out of pocket.
Will a sewer backup be covered automatically? Usually not. You'll need a water backup endorsement, which is often inexpensive to add.
Can I get discounts beyond bundling?
Yes. Ask about security systems, claims-free history, new roofs, and paying your premium in full.
Making the Right Choice for Your Property
The right policy fits your actual house, not an average one. Set dwelling limits based on rebuild cost and choose replacement cost for your belongings. Carry liability limits that protect what you've built. Then close the water gaps that catch so many Harrisburg homeowners off guard: flood coverage, a backup endorsement, and mine subsidence coverage if it applies.
Here's what that means for you this week. Pull out your declarations page, check each limit against the points above, and get at least three quotes from licensed agents. The state's
homeowners insurance help center is a good place to check your rights before you sign. A one-hour review now beats finding a coverage gap while you're standing in two inches of water.
ABOUT THE AUTHOR:
TYLER REITZ, CIC, CPCU, ARM, AU
As Managing Principal of Bowmans Insurance, I’m passionate about helping businesses and individuals protect what matters most with clarity and confidence. With advanced designations including CIC, CPCU, ARM, and AU, I bring a comprehensive approach to risk management—ensuring every client receives strategic, reliable, and personalized coverage.
Contact Us
Why Work With Us?
Why Choose Bowman Insurance Group for Personal Insurance?

Choice and Transparency
Bowman Insurance Group works for you, not the insurance providers. We offer a wide selection of policies from reputable insurers, giving you options that suit your unique needs. We prioritize clarity and honesty, ensuring you understand each policy’s benefits and limitations.

Your Personal Advocate
Our team is committed to more than policy sales—we’re here to serve as your advocate. We balance your coverage needs with affordability, working to provide you with the best value without compromise. Every decision we support is made with your best interests in mind.

Expert Guidance for Life
Insurance can feel complex, but we’re here to make it simple. With years of experience, our advisors explain policies clearly and keep you informed of relevant changes. You’ll receive consistent support from trusted professionals who understand your needs and are dedicated to helping you make informed choices.
About Bowman's Insurance Group
Over 100 years Delivering Exceptional Service to Our Community
Personal Insurance Coverage in Pennsylvania
Personal Insurance Solutions in Pennsylvania
Home
Insurance
Auto
Insurance
Umbrella
Insurance
Condo
Insurance
Boat
Insurance
Motorcycle Insurance
RV
Insurance
ATV
Insurance
Insurance Client Reviews
Read our
customer reviews

40+
Insurance Partners
98%
Client Retention Rate
100
Years in Business
98%
Satisfaction Rate
Process of Working With A Personal Insurance Agent in Pennsylvania
Step 1: Initial Assessment
Our process begins with a comprehensive review of your personal insurance needs. We’ll assess factors like your lifestyle, family needs, and assets, so you get the coverage that best suits your unique situation.
Step 2: Customized Consultation
Meet with our knowledgeable agents one-on-one to discuss options tailored to your requirements. We aim to clarify your choices and recommend the most suitable coverage, considering both quality and affordability.
Step 3: Policy Selection & Activation
Once we identify the right coverage, we’ll handle the paperwork and activate your policy. Our team ensures a smooth, straightforward process, giving you confidence and peace of mind in your coverage.
Our Experts
Meet Our Team of Professional Insurance Experts
Tyler Reitz CIC, CPCU, ARM, AU
President
Carmen Donachy, CISR
Treasurer and Customer Service Rep
Brian Brassell, CSA, CRPC
Investment Advisor Representative, Director of Financial Services Division
Kassie Swope, CIC, CISR, AINS
Commercial Department Manager
Our News & Blogs
Latest insurance news & blogs