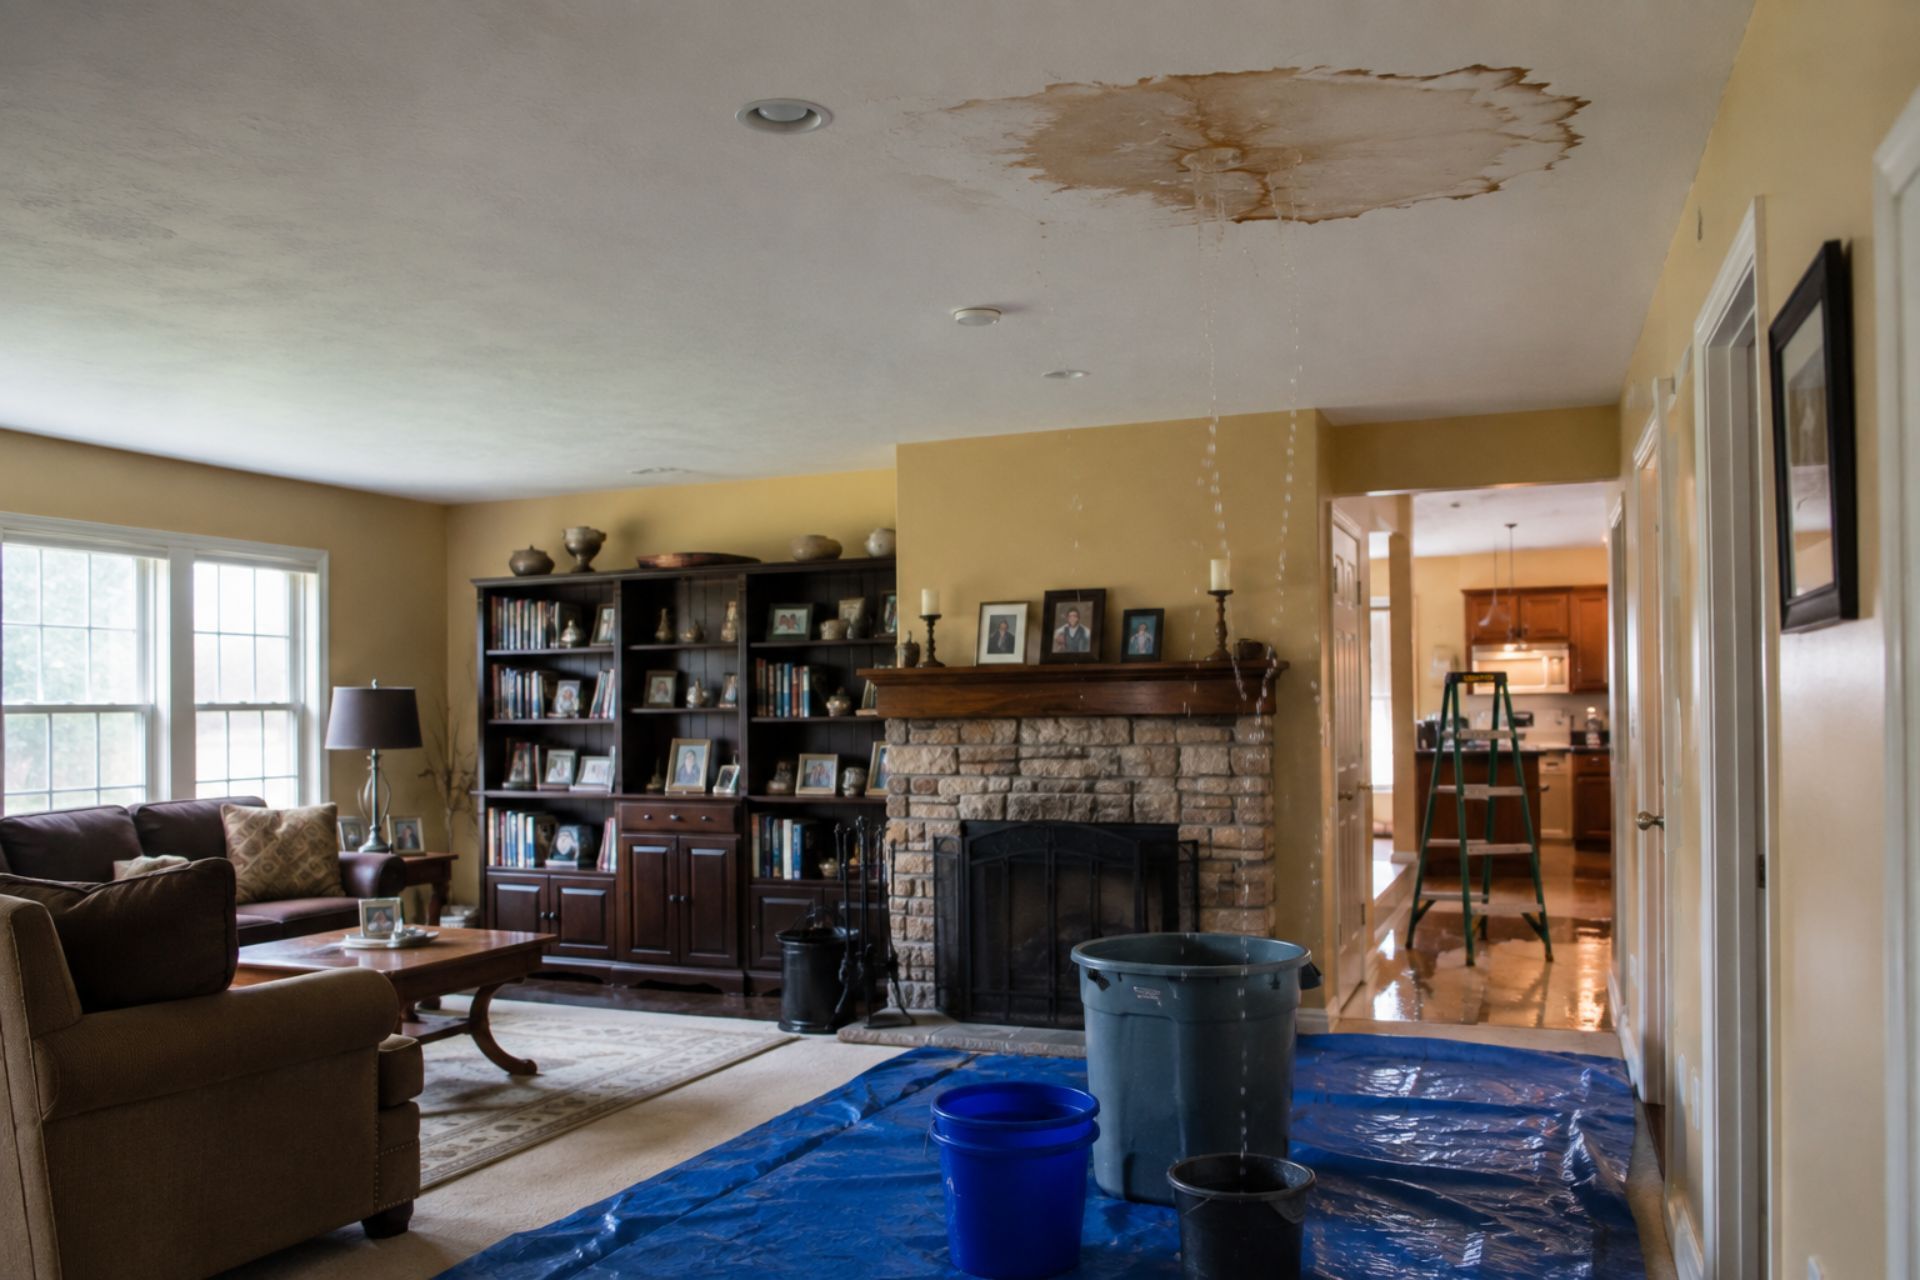

A fire at a downtown Harrisburg restaurant last spring wiped out two years of profit in a single night. The owner had general liability coverage but no commercial property policy, leaving her to cover $180,000 in equipment and build-out costs out of pocket. Stories like this one play out across central Pennsylvania every year, and they're almost always preventable with the right insurance stack.
Whether you run a tech startup near the Capitol Complex or a contracting firm in Steelton, business insurance in Harrisburg covers a wide range of exposures: general liability, property, commercial auto, workers' compensation, cyber liability, and more. Getting the mix right protects your revenue, your employees, and your ability to keep operating after the unexpected. The cost of that protection depends on your industry, headcount, claims history, and where exactly in the Harrisburg metro you're located.
This guide breaks down the core coverage types, what drives pricing in central PA, and practical ways to keep premiums manageable without leaving gaps in your protection.
Essential Business Insurance for Harrisburg Entrepreneurs
Harrisburg's economy blends government contracting, healthcare, logistics, and a growing tech sector. Each industry carries its own risk profile, but a handful of coverage types show up on nearly every commercial policy. Understanding what each one does, and where it stops, keeps you from paying for overlap or missing a critical gap.
General Liability: The Foundation of Protection
General liability (GL) covers third-party bodily injury, property damage, and advertising injury claims. If a client slips on your office floor or you accidentally damage a customer's property during a service call, GL responds. Most commercial leases in Harrisburg require tenants to carry at least $1 million per occurrence.
What GL doesn't cover matters just as much. It won't pay for professional errors, employee injuries, or damage to your own building. That's why it's a foundation, not a complete solution. Industry forecasters suggest budgeting for at least a 10% increase on liability renewals in 2026 due to the growing influence of third-party litigation funding. If your current policy is up for renewal, request quotes early to lock in competitive terms.
Pennsylvania Workers' Compensation Requirements
Pennsylvania law requires nearly every employer to carry workers' compensation insurance, even if you only have one employee. The penalties for non-compliance are steep: criminal misdemeanor charges, fines up to $2,500 per day, and personal liability for all medical costs and lost wages.
The good news for Harrisburg businesses is that the Pennsylvania Insurance Department approved a 1.22% decrease in workers' compensation loss costs effective April 1, 2026, continuing a multi-year trend of declining rates. Your actual premium depends on classification codes, payroll size, and your experience modification factor. A restaurant with ten employees will pay a very different rate than a roofing contractor with the same headcount. Review your classification codes annually, because a single misclassification can inflate your premium by thousands of dollars.
Commercial Property Insurance for Local Storefronts
If you own or lease a physical space, commercial property insurance covers your building (if you own it), equipment, inventory, signage, and often business income lost during a covered event. Flood damage is excluded from standard policies, which is worth noting for businesses near the Susquehanna River or in documented flood zones.
The pricing environment is favorable right now. Commercial property rates in the U.S.
fell by an average of 13% in Q2 2026, marking the eighth consecutive quarter of reductions. If you haven't shopped your property policy recently, 2026 is a strong year to do it. Make sure your policy reflects current replacement costs, not the original purchase price of your equipment.
By: Tyler Reitz
Managing Principal of Bowmans Insurance
Business owners often confuse general liability with professional liability, and the distinction matters. GL covers physical incidents and property damage. Professional liability (also called errors and omissions, or E&O) covers financial harm caused by your advice, services, or failure to deliver on a contract. A marketing agency that runs the wrong ad campaign needs E&O. A plumber who floods a client's basement needs GL.
Comparison Table: General Liability vs. Professional Liability
| Feature | General Liability | Professional Liability (E&O) |
|---|---|---|
| Covers | Bodily injury, property damage, advertising injury | Professional errors, negligent advice, missed deadlines |
| Who needs it | Nearly every business | Service-based and consulting firms |
| Typical limit | $1M per occurrence / $2M aggregate | $1M per claim / $1M aggregate |
| Common claims | Slip-and-fall, damaged client property | Contract disputes, design errors, data mistakes |
| Required by lease/contract? | Almost always | Often required by client contracts |
| Covers your own property? | No | No |
If your business provides professional advice or services, you likely need both policies. Bundling them through the same carrier often qualifies you for a multi-policy discount.
Factors Influencing Insurance Costs in Central PA
Premiums aren't random. Insurers use specific variables to price your risk, and understanding those variables gives you real negotiating power.
Industry Risk and Employee Count
A five-person accounting firm and a five-person demolition crew will see wildly different premiums. Insurers assign classification codes based on your primary business activity, and those codes carry base rates that reflect historical claim frequency and severity. Workers' comp rates in Pennsylvania are published by the PCRB and vary dramatically by trade.
Employee count drives workers' comp and group health costs directly, since premiums are calculated per $100 of payroll. Revenue affects GL pricing. The more you earn, the more exposure insurers assume you carry. A $3 million revenue contractor will pay more for the same GL limits than a $500,000 revenue contractor in the same classification.
Location Impact: Harrisburg City vs. Dauphin County Suburbs
Where your business sits within the metro area changes your rates. Harrisburg city addresses tend to carry slightly higher property and auto premiums due to density, crime statistics, and fire response times. Suburban locations in Lower Paxton, Mechanicsburg, or Hershey often see lower base rates for the same coverage.
The Harrisburg-York-Camp Hill corridor is
one of Pennsylvania's most affordable markets for commercial auto, with full-coverage rates running significantly lower than in Philadelphia. That said, the Pennsylvania Insurance Department's rate review team works to ensure rates are not excessive statewide, so even urban Harrisburg businesses benefit from regulatory oversight. As of July 1, 2026, the accident surcharge threshold for PA auto insurance increased to $2,350, meaning your insurer can't penalize you for small aggregate claims below that cap over three years.
You don't have to accept the first quote you receive. Several proven strategies can reduce your costs without reducing your coverage.
Bundling with a Business Owner's Policy (BOP)
A Business Owner's Policy combines general liability and commercial property into a single package, often at 10-15% less than buying them separately. Most BOPs also include business interruption coverage, which pays for lost income if a covered event forces you to close temporarily. For small to mid-sized Harrisburg businesses, a BOP is often the most cost-effective starting point.
Not every business qualifies. High-hazard operations, companies with large payrolls, or businesses needing very high limits may need standalone policies. But if your annual revenue is under $5 million and you occupy a modest commercial space, a BOP is worth quoting.
Implementing Safety and Risk Management Protocols
Insurers reward businesses that actively reduce risk. Documented safety programs, employee training logs, and regular equipment maintenance can lower your experience modification rate for workers' comp and qualify you for credits on other policies.
Simple steps make a real difference. Install security cameras and monitored alarm systems. Require written safety protocols for any employee operating vehicles or heavy equipment. Conduct quarterly safety meetings and keep attendance records. These actions create a paper trail that your agent can present to underwriters during renewal negotiations. One Harrisburg HVAC contractor I've seen reduced his workers' comp premium by 18% over two years simply by implementing a formal return-to-work program and documenting every safety meeting.
Common Questions About Harrisburg Business Coverage
Do I need cyber liability insurance if I'm a small local business? Yes, if you store any customer data, process credit cards, or use email for financial transactions. Business email compromise and funds transfer fraud now account for 58% of all cyber claims, surpassing ransomware. Small businesses are frequent targets because they often lack dedicated IT security.
How much does general liability cost for a small Harrisburg business? For low-risk businesses like consultants or retail shops, expect to pay roughly $400 to $1,200 per year for a $1M/$2M policy. Higher-risk trades like construction or food service will pay more. Your claims history and revenue are the biggest pricing factors.
Can I get workers' comp if I'm a sole proprietor with no employees? Pennsylvania doesn't require sole proprietors to carry workers' comp for themselves, but you can elect coverage. Some general contractors require subcontractors to carry it regardless of employee count, so check your contract terms.
What's the difference between "claims-made" and "occurrence" policies? An occurrence policy covers incidents that happen during the policy period, no matter when the claim is filed. A claims-made policy only covers claims filed while the policy is active. If you cancel a claims-made policy, you'll need "tail coverage" to protect against late-filed claims.
Is flood insurance included in my commercial property policy? No. Standard commercial property policies exclude flood damage. Businesses near the Susquehanna or in FEMA-designated flood zones should purchase a separate flood policy through the National Flood Insurance Program or a private carrier.
Making the Right Choice for Your Company
Picking the right business insurance in Harrisburg means matching your actual exposures to the right policies, not buying the cheapest option or the most expensive one. Start by listing every risk your business faces: customer injuries, employee accidents, vehicle use, professional errors, data breaches, and property damage. Then build coverage around those specific risks.
The 2026 market is working in your favor on several fronts. Workers' comp loss costs are down, commercial property rates continue to fall, and the Harrisburg metro remains one of the more affordable insurance markets in Pennsylvania. Take advantage of that by shopping your policies, bundling where it makes sense, and investing in safety programs that pay for themselves through lower premiums.
Talk to an independent agent who writes policies across multiple carriers. They can compare pricing and coverage terms in ways a single-carrier agent can't. Bring your current declarations pages, your payroll records, and a list of your vehicles and equipment. The more information you provide upfront, the more accurate your quotes will be, and the less likely you are to discover a gap when you need coverage most.
ABOUT THE AUTHOR:
TYLER REITZ, CIC, CPCU, ARM, AU
As Managing Principal of Bowmans Insurance, I’m passionate about helping businesses and individuals protect what matters most with clarity and confidence. With advanced designations including CIC, CPCU, ARM, and AU, I bring a comprehensive approach to risk management—ensuring every client receives strategic, reliable, and personalized coverage.
Contact Us
Why Work With Us?
Why Choose Bowman Insurance Group for Personal Insurance?

Choice and Transparency
Bowman Insurance Group works for you, not the insurance providers. We offer a wide selection of policies from reputable insurers, giving you options that suit your unique needs. We prioritize clarity and honesty, ensuring you understand each policy’s benefits and limitations.

Your Personal Advocate
Our team is committed to more than policy sales—we’re here to serve as your advocate. We balance your coverage needs with affordability, working to provide you with the best value without compromise. Every decision we support is made with your best interests in mind.

Expert Guidance for Life
Insurance can feel complex, but we’re here to make it simple. With years of experience, our advisors explain policies clearly and keep you informed of relevant changes. You’ll receive consistent support from trusted professionals who understand your needs and are dedicated to helping you make informed choices.
About Bowman's Insurance Group
Over 100 years Delivering Exceptional Service to Our Community
Personal Insurance Coverage in Pennsylvania
Personal Insurance Solutions in Pennsylvania
Home
Insurance
Auto
Insurance
Umbrella
Insurance
Condo
Insurance
Boat
Insurance
Motorcycle Insurance
RV
Insurance
ATV
Insurance
Insurance Client Reviews
Read our
customer reviews

40+
Insurance Partners
98%
Client Retention Rate
100
Years in Business
98%
Satisfaction Rate
Process of Working With A Personal Insurance Agent in Pennsylvania
Step 1: Initial Assessment
Our process begins with a comprehensive review of your personal insurance needs. We’ll assess factors like your lifestyle, family needs, and assets, so you get the coverage that best suits your unique situation.
Step 2: Customized Consultation
Meet with our knowledgeable agents one-on-one to discuss options tailored to your requirements. We aim to clarify your choices and recommend the most suitable coverage, considering both quality and affordability.
Step 3: Policy Selection & Activation
Once we identify the right coverage, we’ll handle the paperwork and activate your policy. Our team ensures a smooth, straightforward process, giving you confidence and peace of mind in your coverage.
Our Experts
Meet Our Team of Professional Insurance Experts
Tyler Reitz CIC, CPCU, ARM, AU
President
Carmen Donachy, CISR
Treasurer and Customer Service Rep
Brian Brassell, CSA, CRPC
Investment Advisor Representative, Director of Financial Services Division
Kassie Swope, CIC, CISR, AINS
Commercial Department Manager
Our News & Blogs
Latest insurance news & blogs