Hershey, Pennsylvania
General Liability Insurance

See How We're Different:
Call Us: 717-838-5464
A chocolate factory tour goes sideways when a visitor slips on a wet floor, breaking a wrist and threatening a $200,000 lawsuit. A food truck at a Hersheypark event accidentally backs into a vendor's display, destroying $15,000 in merchandise. These aren't hypothetical scenarios for Hershey business owners: they're the kind of claims that arrive without warning and drain bank accounts fast.
General liability insurance protects Hershey, Pennsylvania businesses from the financial fallout of bodily injury claims, property damage, and related legal costs. Whether you run a retail shop on Chocolate Avenue, a contracting company near Palmdale, or a seasonal attraction tied to the tourism economy, understanding your coverage limits, exclusions, additional insured requirements, and costs is the difference between surviving a claim and shutting your doors. This guide breaks down what Hershey business owners actually need to know about GL policies in 2026, with specific attention to Pennsylvania regulations and local market conditions.
Understanding General Liability Insurance for Hershey Businesses
General liability insurance, often called GL or CGL (commercial general liability), is the foundational coverage that protects your business when someone who isn't an employee gets hurt on your property or because of your operations. It also covers damage your business causes to someone else's property. For Hershey businesses, this policy is often the first one a landlord, event organizer, or general contractor will ask to see before signing any agreement.
Why Hershey Business Owners Need Protection
Hershey's economy is uniquely tied to tourism, hospitality, and food service. Millions of visitors pass through the area each year, and that foot traffic creates exposure. A restaurant owner faces slip-and-fall risk every time a guest walks through the door. A landscaping company working near a hotel property could accidentally damage irrigation systems worth tens of thousands of dollars. Liability risk trends across Pennsylvania have been shifting toward higher claim severity, which means even routine incidents can result in expensive settlements. Without a GL policy, you'd be paying attorneys, medical bills, and repair costs out of pocket.
Common Risks: Bodily Injury and Property Damage
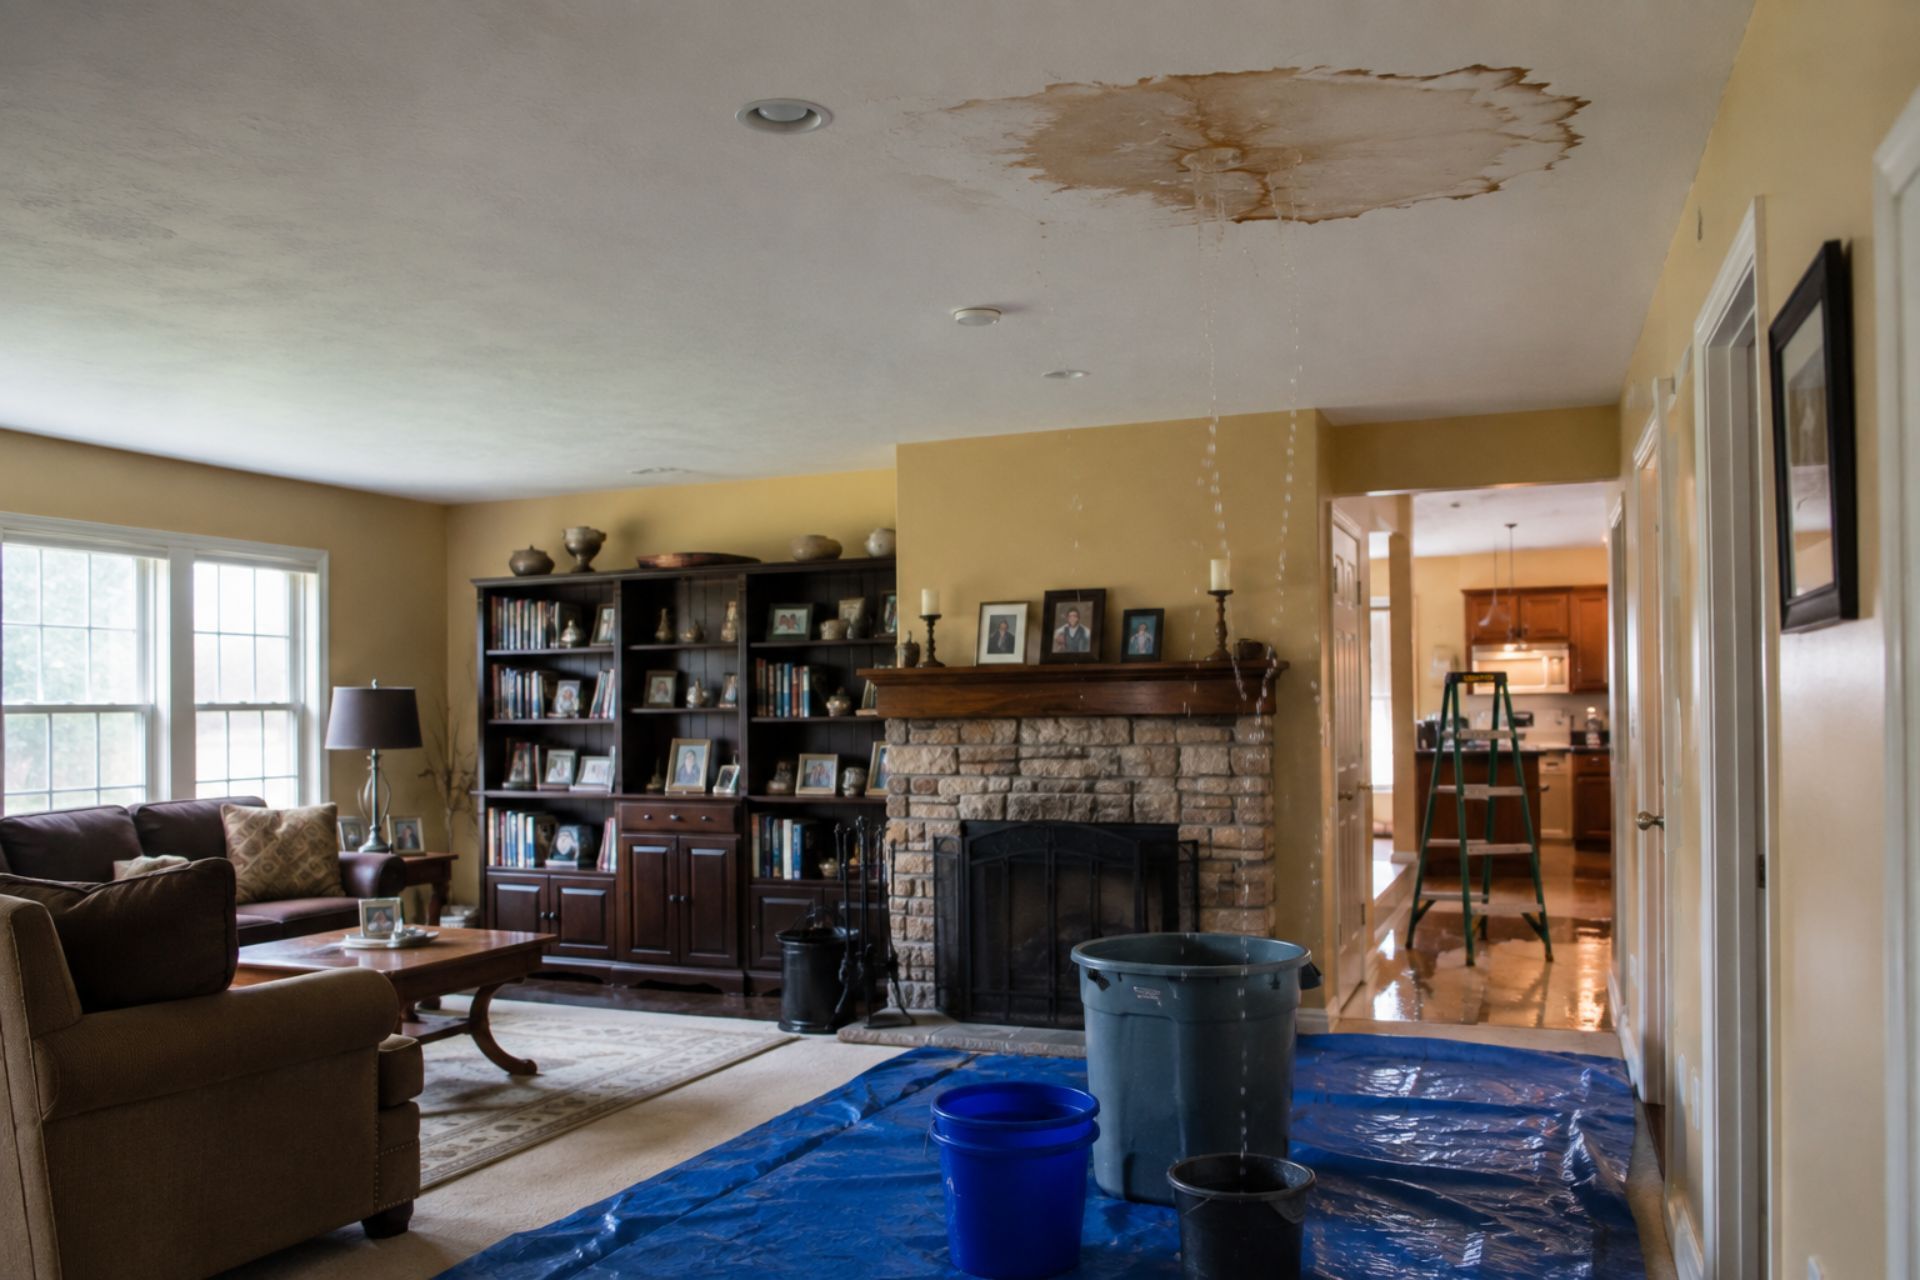
Bodily injury claims are the most frequent GL triggers for Hershey businesses. A customer trips over a loose floor mat, a delivery driver gets hit by a falling sign, or a child at a birthday party venue gets burned by hot equipment. Property damage claims are the second major category: think of a plumber who accidentally floods a client's basement or an electrician whose work causes a small fire. Both categories are covered under a standard GL policy, including the
legal defense costs even if the claim turns out to be baseless. That defense coverage alone can save you $50,000 or more on a single frivolous lawsuit.
By: Tyler Reitz
Managing Principal of Bowmans Insurance
Coverage Limits and Policy Structure
Your GL policy isn't unlimited protection. Every policy has defined caps that determine the maximum your insurer will pay, and understanding those caps is critical before you sign.
Occurrence vs. Aggregate Limits
Two numbers matter most on your declarations page. The per-occurrence limit is the maximum your insurer pays for any single incident. The aggregate limit is the total your insurer will pay across all claims during the policy period, typically one year. About 91% of Pennsylvania small business owners carry the standard benchmark of $1 million per occurrence and $2 million aggregate, which satisfies most lease and contract requirements. Some businesses, especially those with high foot traffic or those working on larger commercial projects, need higher limits and purchase an umbrella or excess liability policy to get there.
Comparison: Basic vs. Extended Liability Coverage
| Feature | Basic GL Policy | Extended GL Policy |
|---|---|---|
| Per-Occurrence Limit | $1,000,000 | $2,000,000+ |
| Aggregate Limit | $2,000,000 | $4,000,000+ |
| Products/Completed Ops | Included (standard sub-limit) | Higher sub-limits available |
| Personal/Advertising Injury | Included | Included with broader terms |
| Medical Payments | $5,000 per person | $10,000+ per person |
| Hired/Non-Owned Auto | Typically excluded | Often endorsed |
| Typical Annual Cost | $500 - $1,500 | $1,500 - $4,000+ |
The basic policy works for many sole proprietors and low-risk office businesses. If you're a contractor,
event planner, or business with significant public interaction, extended coverage is worth the added premium.
One of the most misunderstood parts of a GL policy is the additional insured endorsement. If you've ever been asked to "add someone to your policy," this is what they're talking about.
When to Add a Third Party to Your Policy
Landlords, general contractors, and event venues routinely require tenants and subcontractors to name them as additional insureds. This means your policy extends coverage to that third party for claims arising from your work or your use of their property. A Hershey bakery leasing space in a strip mall will almost certainly need to add the property management company. A subcontractor working on a renovation project at the Hotel Hershey would need to add the GC. The requirement for additional insured endorsements has become standard in commercial contracts, and refusing to comply usually means losing the deal.
Impact on Claims and Premium Costs
Adding an additional insured doesn't always increase your premium significantly. Many standard GL policies include a blanket additional insured endorsement at no extra charge, covering anyone you're contractually required to add. The catch is that when a claim occurs, your policy responds first. If a visitor sues both you and your landlord, your insurer handles the defense for both parties under your limits. That means your aggregate gets eaten faster. For businesses juggling multiple contracts, this erosion of limits is a real concern, and it's one reason to consider carrying higher aggregate limits or an umbrella policy.
What Isn't Covered: Common Policy Exclusions
Every GL policy has a list of things it won't pay for. Knowing these exclusions before a claim hits is far more useful than discovering them after.
Professional Errors vs. General Liability
GL covers bodily injury and property damage caused by your operations, but it doesn't cover mistakes in your professional advice or services. An accountant who gives bad tax guidance, a consultant who delivers a flawed business plan, or an architect whose design has structural errors: none of those are GL claims. They fall under professional liability (errors and omissions) insurance instead. Hershey businesses that provide any kind of professional service or consultation need both policies. A common and expensive mistake is assuming GL handles everything.
Employee Injuries and Workers' Compensation
If one of your employees gets hurt on the job, your GL policy won't cover it. Pennsylvania requires most employers to carry workers' compensation insurance, and GL policies contain an explicit exclusion for employee injuries. The same goes for employment practices claims like wrongful termination or harassment suits, which require a separate EPLI policy. Pennsylvania's insurance department has been updating filing requirements for carriers, so make sure your agent confirms your workers' comp policy meets current state standards.
Other common GL exclusions include pollution liability, intentional acts, damage to your own property, auto-related incidents (covered by commercial auto), and liquor liability for businesses that serve alcohol.
Factors Influencing Insurance Costs in Pennsylvania
What you'll pay for general liability coverage in Hershey depends on several variables, and understanding them gives you some control over your premium.
Your industry classification is the biggest factor. A retail candy shop pays far less than a roofing contractor because the risk profiles are completely different. Pennsylvania contractors typically face higher premiums due to physical risk exposure, with annual GL costs ranging from $800 to $3,500 depending on trade and revenue. Revenue and payroll size also matter: a business generating $2 million annually will pay more than one generating $200,000, because insurers assume more revenue means more customer interactions and more exposure.
Your claims history plays a significant role too. A clean record for three to five years earns you better rates, while even a single large claim can push premiums up 15% to 30% at renewal. Location within Pennsylvania matters as well. Hershey sits in Dauphin County, which has moderate litigation trends compared to Philadelphia, where jury awards tend to run higher. The broader Pennsylvania insurance market in 2026 has shown strong underwriting results in the first half of the year, which could help stabilize or even reduce rates for well-managed businesses. Several factors are driving insurance rate changes across the state, including inflation in repair costs and medical expenses.
Common Questions About Hershey Business Insurance
How much does a basic GL policy cost for a small Hershey business? Most small businesses in Hershey pay between $500 and $1,800 per year for a standard $1M/$2M policy. Low-risk businesses like consultants or small retailers land on the lower end, while contractors and food service businesses pay more.
Do I need GL insurance if I work from home? Yes, if clients or vendors ever visit your home office, or if your work could cause property damage or injury to a third party. Your homeowner's policy won't cover business-related claims.
Can I bundle GL with other business insurance? A Business Owner's Policy (BOP) bundles GL with commercial property insurance, usually at a discount of 10% to 15% compared to buying them separately. Most Hershey small businesses benefit from a BOP.
What happens if my claim exceeds my coverage limit? You're personally responsible for the amount above your policy limit. This is why umbrella policies exist: they kick in after your GL limits are exhausted, providing an extra layer of protection.
Does my GL policy cover me at off-site events like Hershey festivals? Standard GL policies cover your operations wherever they take place, including off-site events. That said, event organizers may require specific additional insured endorsements and minimum coverage limits before allowing you to participate.
How quickly can I get a GL policy? Many insurers offer same-day or next-day binding for straightforward risks. Contractors and higher-risk businesses may need a few days for underwriting review. Your
small business GL coverage can often be quoted within hours.
Making the Right Choice for Your Local Business
Picking the right GL policy for your Hershey business isn't about finding the cheapest option: it's about matching your actual risk profile to the right coverage structure. A $1M/$2M policy handles most situations, but your specific industry, contract requirements, and growth plans should drive the decision.
Start by listing every contract, lease, and vendor agreement that requires insurance. Check the minimum limits and additional insured requirements in each one. Then talk to an independent agent who writes commercial policies in Pennsylvania, not just a national call center. Local agents understand Dauphin County's business environment and can flag coverage gaps that generic online quotes miss.
Review your policy annually, especially if your revenue changes, you hire employees, or you take on new types of work. A policy that fit your business two years ago may leave you exposed today. The best time to find a coverage gap is during a policy review, not during a claim.
ABOUT THE AUTHOR:
TYLER REITZ, CIC, CPCU, ARM, AU
As Managing Principal of Bowmans Insurance, I’m passionate about helping businesses and individuals protect what matters most with clarity and confidence. With advanced designations including CIC, CPCU, ARM, and AU, I bring a comprehensive approach to risk management—ensuring every client receives strategic, reliable, and personalized coverage.
Contact Us
Why Work With Us?
Why Choose Bowman Insurance Group for Personal Insurance?

Choice and Transparency
Bowman Insurance Group works for you, not the insurance providers. We offer a wide selection of policies from reputable insurers, giving you options that suit your unique needs. We prioritize clarity and honesty, ensuring you understand each policy’s benefits and limitations.

Your Personal Advocate
Our team is committed to more than policy sales—we’re here to serve as your advocate. We balance your coverage needs with affordability, working to provide you with the best value without compromise. Every decision we support is made with your best interests in mind.

Expert Guidance for Life
Insurance can feel complex, but we’re here to make it simple. With years of experience, our advisors explain policies clearly and keep you informed of relevant changes. You’ll receive consistent support from trusted professionals who understand your needs and are dedicated to helping you make informed choices.
About Bowman's Insurance Group
Over 100 years Delivering Exceptional Service to Our Community
Personal Insurance Coverage in Pennsylvania
Personal Insurance Solutions in Pennsylvania
Home
Insurance
Auto
Insurance
Umbrella
Insurance
Condo
Insurance
Boat
Insurance
Motorcycle Insurance
RV
Insurance
ATV
Insurance
Insurance Client Reviews
Read our
customer reviews

40+
Insurance Partners
98%
Client Retention Rate
100
Years in Business
98%
Satisfaction Rate
Process of Working With A Personal Insurance Agent in Pennsylvania
Step 1: Initial Assessment
Our process begins with a comprehensive review of your personal insurance needs. We’ll assess factors like your lifestyle, family needs, and assets, so you get the coverage that best suits your unique situation.
Step 2: Customized Consultation
Meet with our knowledgeable agents one-on-one to discuss options tailored to your requirements. We aim to clarify your choices and recommend the most suitable coverage, considering both quality and affordability.
Step 3: Policy Selection & Activation
Once we identify the right coverage, we’ll handle the paperwork and activate your policy. Our team ensures a smooth, straightforward process, giving you confidence and peace of mind in your coverage.
Our Experts
Meet Our Team of Professional Insurance Experts
Tyler Reitz CIC, CPCU, ARM, AU
President
Carmen Donachy, CISR
Treasurer and Customer Service Rep
Brian Brassell, CSA, CRPC
Investment Advisor Representative, Director of Financial Services Division
Kassie Swope, CIC, CISR, AINS
Commercial Department Manager
Our News & Blogs
Latest insurance news & blogs