Hershey, Pennsylvania
Workers' Compensation Insurance

See How We're Different:
Call Us: 717-838-5464
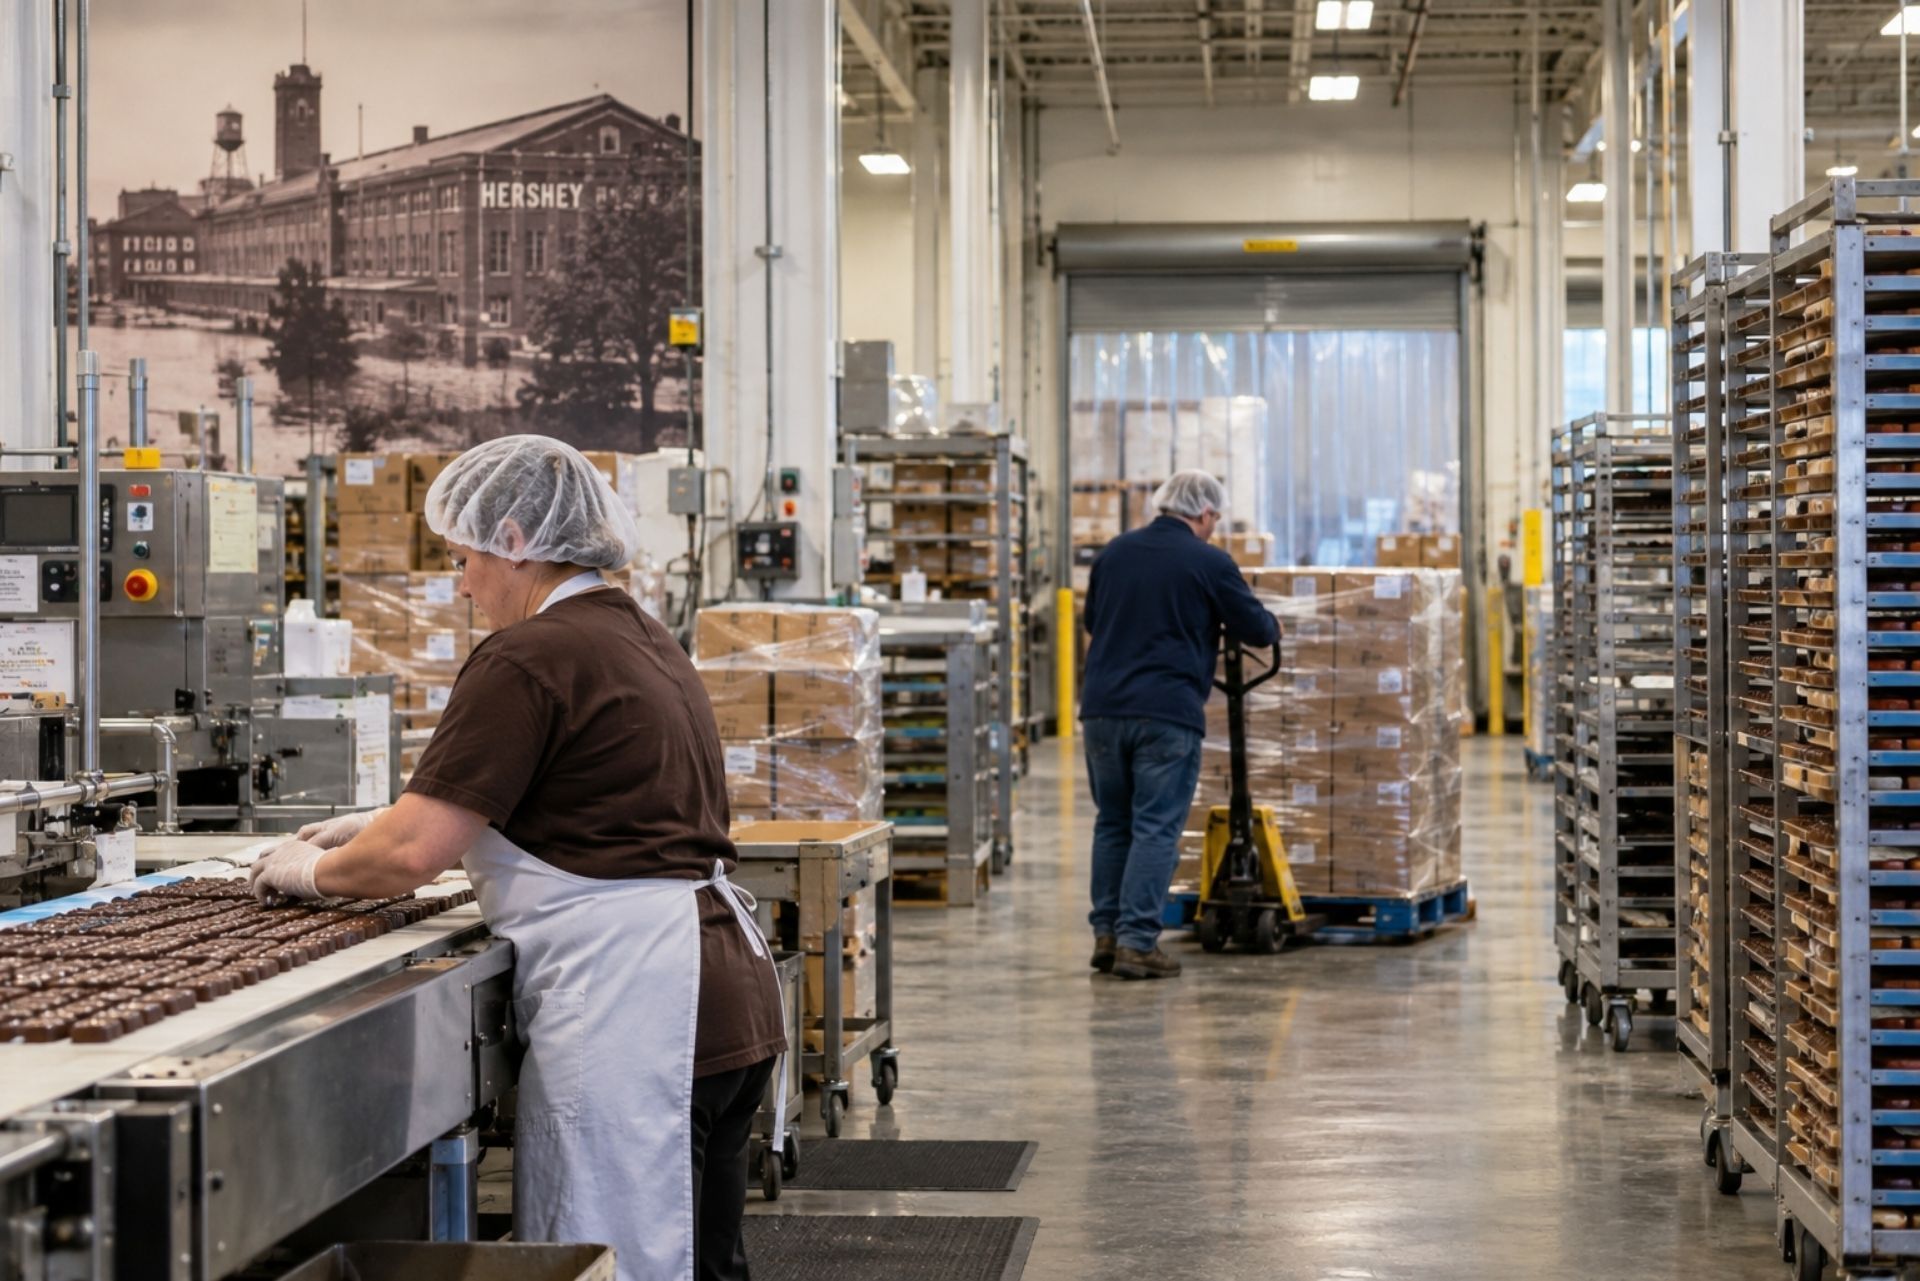
A chocolate factory tour bus collides with a delivery truck on Chocolate Avenue, sending three workers to the hospital. The employer's first call isn't to a lawyer or an insurance agent: it's to find out whether their workers' comp policy is current. For businesses operating in Hershey, Pennsylvania, that policy isn't optional. It's a legal requirement that protects both employees and the companies that employ them.
Hershey sits within Derry Township in Dauphin County, and while the town is famous for its sweet exports, its economy extends well beyond confections. Tourism, healthcare, education, logistics, and manufacturing all contribute to a diverse local workforce. Each of these industries carries its own set of workplace risks, and Pennsylvania law demands that employers carry coverage to address them. Workers' compensation insurance in Hershey covers medical expenses, lost wages, and rehabilitation costs for employees injured on the job, regardless of fault.
Pennsylvania's workers' comp system has seen notable changes heading into 2026. The
maximum weekly compensation rate for 2026 is $1,394.00, reflecting a 3.5% increase tied to the statewide average weekly wage. That number directly affects what injured workers receive and what employers should budget for. Whether you run a
small candy shop on Cocoa Avenue or manage a warehouse near the Hershey Medical Center, understanding your obligations, exemptions, class codes, and claims procedures is essential to staying compliant and
controlling costs.
Understanding Pennsylvania Workers' Comp Mandates for Hershey Businesses
Pennsylvania's Workers' Compensation Act applies broadly, and Hershey employers aren't exempt from its reach. The state treats workers' comp as a no-fault system, meaning employees don't need to prove their employer was negligent to receive benefits. In return, employers gain protection from most personal injury lawsuits filed by injured workers.
Employer Coverage Requirements
Every Pennsylvania employer must provide workers' compensation coverage from the moment they hire their first employee. There's no waiting period, no minimum number of hours worked, and no threshold based on payroll size. Part-time, seasonal, and full-time workers all qualify for coverage.
Employers in Hershey can obtain coverage through three channels: purchasing a policy from a licensed private insurance carrier, applying for coverage through the State Workers' Insurance Fund (SWIF), or, for larger companies, obtaining approval to self-insure. Most small and mid-sized businesses in Derry Township go the private carrier route. Pennsylvania is one of four states that maintain a competitive state fund alongside private insurers, giving employers options when shopping for rates.
Common Exemptions and Exclusions
Not everyone falls under the Act's umbrella. Sole proprietors and general partners can opt out of coverage for themselves, though they must still cover any employees they hire. Certain agricultural laborers, domestic workers employed fewer than 30 days or earning less than $1,300 in a calendar quarter, and some casual employees may also be exempt.
Independent contractors represent a gray area that trips up many Hershey businesses. Pennsylvania applies a multi-factor test to determine whether a worker is truly independent or functionally an employee. Misclassifying an employee as a contractor to avoid workers' comp obligations can result in serious penalties. If you rely on 1099 workers, review those relationships carefully with an attorney or insurance professional.
Penalties for Non-Compliance in PA
Operating without workers' comp insurance in Pennsylvania is a criminal offense. A first violation is classified as a third-degree felony, carrying fines up to $15,000 and potential imprisonment. Each day without coverage can be treated as a separate offense.
Beyond criminal penalties, uninsured employers face civil liability. Injured workers can sue directly for damages, and the state can issue stop-work orders that shut down operations entirely. The Bureau of Workers' Compensation actively investigates complaints and conducts audits. For a Hershey business owner, the risk of going uninsured far outweighs the cost of a policy.
By: Tyler Reitz
Managing Principal of Bowmans Insurance
Your workers' comp premium isn't a flat fee. It's calculated using a formula that factors in your industry classification, payroll, and claims history. Understanding how that formula works gives you real control over what you pay.
How NCCI and PCRB Codes Impact Cost
Pennsylvania is one of the few states that uses its own rating bureau rather than relying solely on the National Council on Compensation Insurance (NCCI). The Pennsylvania Compensation Rating Bureau (PCRB) assigns classification codes and publishes rating values that determine base premium rates for each job type. Each code carries a rate expressed per $100 of payroll.
The basic formula is straightforward: (Payroll / 100) x Class Code Rate x Experience Modification Rate = Annual Premium. Your experience modification rate (EMR) reflects your company's claims history compared to similar businesses. An EMR below 1.0 means you're performing better than average and will pay less. Above 1.0, and you'll pay more. New businesses typically start at 1.0.
Common Hershey Industry Classifications
Hershey's economy generates a wide range of class codes. Here are some you'll commonly encounter:
- Candy or confectionery manufacturing: Code 2041
- Restaurant or food service operations: Code 9082
- Hotel or resort operations: Code 9052
- Clerical office employees: Code 8810
- Healthcare professionals (hospital): Code 8833
- Amusement park or recreation: Code 9016
A single business can carry multiple class codes. A hotel with a restaurant, maintenance crew, and front desk staff will have different rates applied to each group's payroll. Proper classification matters because an incorrect code can mean you're overpaying, or worse, underpaying and facing an audit surcharge.
Managing the Claims Process in Derry Township
Filing a workers' comp claim correctly is just as important as having the policy in the first place. Mistakes during the claims process lead to delayed benefits, disputed claims, and increased costs for employers.
Reporting Workplace Injuries Promptly
Pennsylvania law requires employers to report workplace injuries to their insurance carrier promptly. While there's no strict statutory deadline for the initial report to the insurer, best practice is to report within 24 hours. The insurer then has 21 days to accept or deny the claim.
Employees should notify their employer of a work-related injury within 120 days to preserve their right to benefits. That said, waiting that long creates problems for everyone. Encourage your workers to report injuries the same day they occur. Late reporting is one of the most common reasons claims become contested, and contested claims cost significantly more than straightforward ones.
For injuries resulting in disability lasting more than seven days, employers must file a First Report of Injury with the Bureau of Workers' Compensation. Lost-time claims trigger wage replacement benefits, which in 2026 can reach the maximum weekly rate of $1,394 for total disability.
The Role of Designated Physician Panels
Pennsylvania allows employers to establish a list of at least six designated healthcare providers. For the first 90 days of treatment, injured employees must choose a provider from this panel. After 90 days, they can switch to any licensed provider.
Building a strong panel matters. Include physicians experienced in occupational medicine, orthopedics, and physical therapy. Providers familiar with workers' comp cases tend to manage treatment plans more efficiently, which helps employees recover faster and keeps claim costs lower. If you don't maintain a valid panel, your employee can see any doctor from day one, and you lose that early influence over treatment direction.
Pennsylvania Workers' Comp vs. General Liability
Business owners sometimes confuse workers' compensation with general liability insurance. They serve different purposes, cover different risks, and both are typically necessary.
Comparison of Coverage Types
| Feature | Workers' Compensation | General Liability |
|---|---|---|
| Who it covers | Your employees | Third parties (customers, vendors, public) |
| What it covers | Workplace injuries and occupational illness | Bodily injury, property damage, advertising injury to others |
| Required by law? | Yes, in Pennsylvania for all employers | Not mandated by state law, but often required by contracts |
| Fault-based? | No-fault system | Fault must typically be established |
| Typical claim example | Employee slips on wet floor in your warehouse | Customer slips on wet floor in your store |
| Premium basis | Payroll and class codes | Revenue, square footage, or operations |
A Hershey restaurant needs both. Workers' comp covers the line cook who burns herself on a fryer. General liability covers the customer who slips on a wet tile in the dining room. Carrying one without the other leaves a significant gap in your protection. Pennsylvania's workers' comp rates vary by industry and risk classification, while general liability premiums depend more on your revenue and the nature of your customer interactions.
Common Questions About Hershey Workers' Comp
Do I need workers' comp if I only have one employee? Yes. Pennsylvania requires coverage starting with your very first hire, whether that person works full-time, part-time, or seasonally.
How much does workers' comp insurance cost in Hershey? Costs depend on your class codes, payroll, and EMR. A small office-based business might pay $0.30 per $100 of payroll, while a manufacturing operation could pay $3.00 or more per $100. Get quotes from multiple carriers or through SWIF.
Can I use an out-of-state policy to cover Pennsylvania employees? Only if your policy specifically lists Pennsylvania under Item 3A of the information page. An "all states" endorsement doesn't always include monopolistic or unique-fund states. Confirm with your carrier.
What happens if an employee is injured during a company event? If the event is employer-sponsored and attendance is expected or encouraged, injuries are generally covered. A voluntary happy hour at a bar downtown is less clear-cut than a mandatory team-building exercise at Hersheypark.
How long do workers' comp benefits last in PA? Total disability benefits can continue for up to 500 weeks. Partial disability benefits also have a 500-week cap. Medical benefits related to the work injury have no time limit as long as treatment remains reasonable and necessary.
Can I reduce my premiums without cutting coverage?
Absolutely. Implement a formal safety program, maintain a clean claims history, and review your class code assignments annually. A
workers' comp benefits calculator can help you estimate exposure and plan accordingly.
What This Means for Your Business
Running a business in Hershey means operating within Pennsylvania's workers' comp framework, and that framework doesn't offer much wiggle room. Every employer with at least one employee needs coverage. The penalties for going without it are severe, and the financial exposure from an uninsured workplace injury can be devastating.
Your premiums are not fixed. They respond to the decisions you make: how you classify your workers, how aggressively you manage safety, and how quickly you report and handle claims. A proactive approach to workplace safety and claims management can lower your EMR over time, directly reducing what you pay each year.
Start by confirming your class codes are accurate, your physician panel is current, and your reporting procedures are documented. If you haven't reviewed your policy in the past year, request a fresh quote. Rates shift annually, and the 2026 adjustments mean your current premium may no longer reflect the best available option. Talk to a licensed Pennsylvania insurance agent who understands Derry Township's business mix and can match you with the right coverage at a competitive price.
ABOUT THE AUTHOR:
TYLER REITZ, CIC, CPCU, ARM, AU
As Managing Principal of Bowmans Insurance, I’m passionate about helping businesses and individuals protect what matters most with clarity and confidence. With advanced designations including CIC, CPCU, ARM, and AU, I bring a comprehensive approach to risk management—ensuring every client receives strategic, reliable, and personalized coverage.
Contact Us
Why Work With Us?
Why Choose Bowman Insurance Group for Personal Insurance?

Choice and Transparency
Bowman Insurance Group works for you, not the insurance providers. We offer a wide selection of policies from reputable insurers, giving you options that suit your unique needs. We prioritize clarity and honesty, ensuring you understand each policy’s benefits and limitations.

Your Personal Advocate
Our team is committed to more than policy sales—we’re here to serve as your advocate. We balance your coverage needs with affordability, working to provide you with the best value without compromise. Every decision we support is made with your best interests in mind.

Expert Guidance for Life
Insurance can feel complex, but we’re here to make it simple. With years of experience, our advisors explain policies clearly and keep you informed of relevant changes. You’ll receive consistent support from trusted professionals who understand your needs and are dedicated to helping you make informed choices.
About Bowman's Insurance Group
Over 100 years Delivering Exceptional Service to Our Community
Personal Insurance Coverage in Pennsylvania
Personal Insurance Solutions in Pennsylvania
Home
Insurance
Auto
Insurance
Umbrella
Insurance
Condo
Insurance
Boat
Insurance
Motorcycle Insurance
RV
Insurance
ATV
Insurance
Insurance Client Reviews
Read our
customer reviews

40+
Insurance Partners
98%
Client Retention Rate
100
Years in Business
98%
Satisfaction Rate
Process of Working With A Personal Insurance Agent in Pennsylvania
Step 1: Initial Assessment
Our process begins with a comprehensive review of your personal insurance needs. We’ll assess factors like your lifestyle, family needs, and assets, so you get the coverage that best suits your unique situation.
Step 2: Customized Consultation
Meet with our knowledgeable agents one-on-one to discuss options tailored to your requirements. We aim to clarify your choices and recommend the most suitable coverage, considering both quality and affordability.
Step 3: Policy Selection & Activation
Once we identify the right coverage, we’ll handle the paperwork and activate your policy. Our team ensures a smooth, straightforward process, giving you confidence and peace of mind in your coverage.
Our Experts
Meet Our Team of Professional Insurance Experts
Tyler Reitz CIC, CPCU, ARM, AU
President
Carmen Donachy, CISR
Treasurer and Customer Service Rep
Brian Brassell, CSA, CRPC
Investment Advisor Representative, Director of Financial Services Division
Kassie Swope, CIC, CISR, AINS
Commercial Department Manager
Our News & Blogs
Latest insurance news & blogs