Harrisburg, PA General Liability Insurance

See How We're Different:
Call Us: 717-838-5464
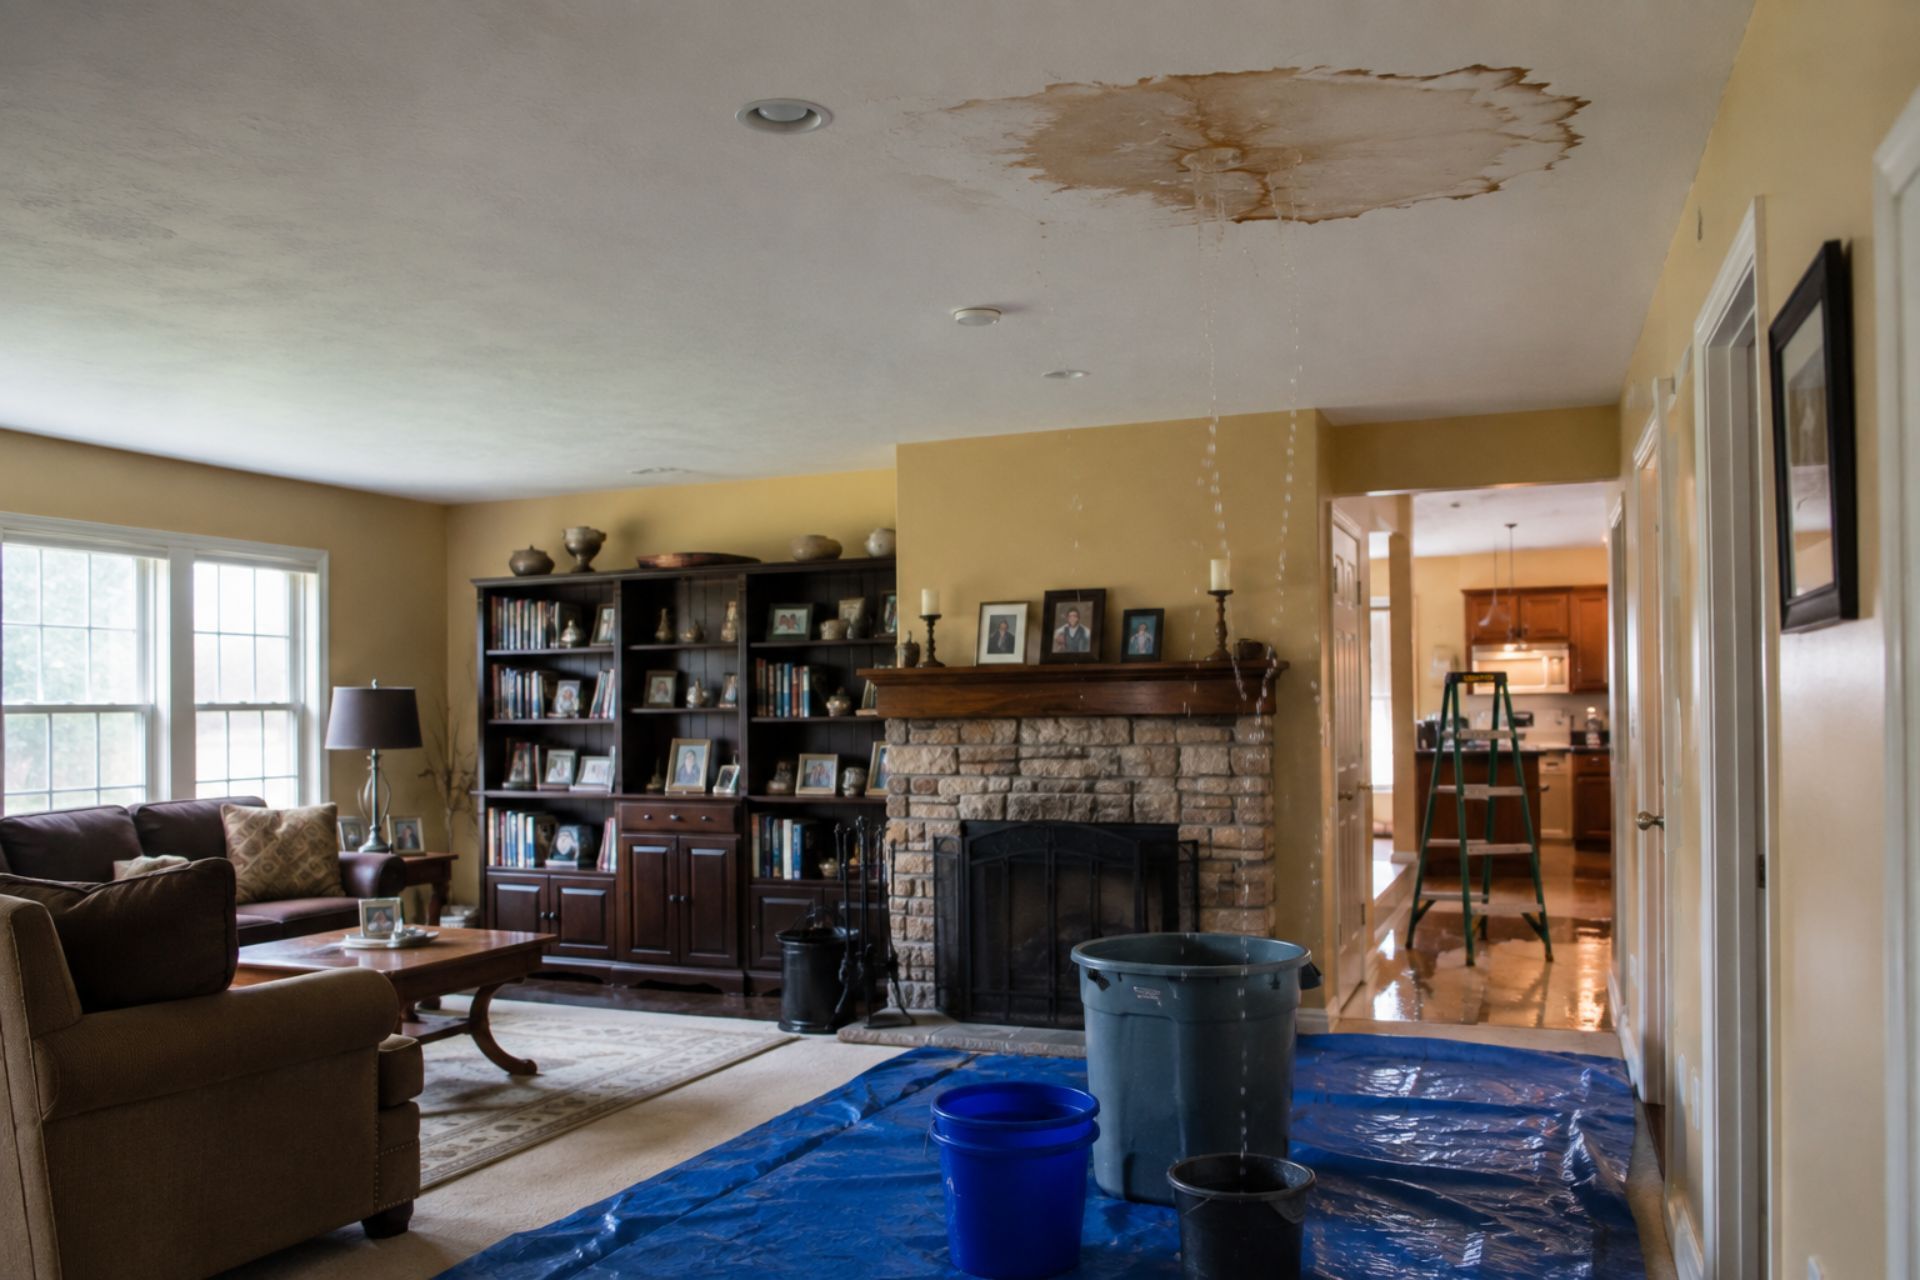
A Harrisburg plumber finishes a bathroom remodel, and three days later the homeowner calls: a pipe joint failed, flooding the first floor and destroying hardwood floors worth thousands. A landscaping crew in Midtown accidentally damages a client's retaining wall while grading a slope. A customer trips over equipment left in a doorway at a small retail shop on Second Street. These aren't hypothetical situations. They're the kinds of claims that can bankrupt a small business without the right insurance.
If you own or operate a business in the Harrisburg area, understanding
general liability insurance, including coverage limits, bodily injury and property damage claims, additional insureds, exclusions, and costs, isn't optional. It's the foundation of protecting everything you've built. This guide breaks down what you need to know, with a focus on Pennsylvania-specific rules and the realities of doing business in central PA.
Why Harrisburg Small Businesses Need General Liability Insurance
Running a business in Harrisburg means dealing with foot traffic, client interactions, subcontractor relationships, and physical job sites. Every one of those touchpoints creates exposure. A single slip-and-fall claim or property damage lawsuit can generate legal fees and settlements that dwarf your annual revenue.
General liability insurance (often called CGL, for commercial general liability) is the policy that responds to those third-party claims. It pays for legal defense, settlements, and judgments when someone who isn't your employee gets hurt or their property is damaged because of your business operations.
Common Risks for Local Service Providers
Contractors, restaurants, retail shops, and professional service firms in Harrisburg all face distinct risks. A general contractor might damage an adjacent property during demolition. A restaurant could face a claim after a customer slips on a wet floor. Even a consultant working from a home office could be sued if a client trips during a meeting.
The common thread is third-party exposure. If your business interacts with anyone outside your own payroll, whether customers, vendors, or the general public, you carry liability risk. CGL is designed to absorb that risk before it hits your personal or business bank accounts.
Pennsylvania Legal Requirements and Industry Standards
Pennsylvania doesn't have a blanket state law requiring every business to carry general liability insurance. But that doesn't mean you can skip it. Many Harrisburg landlords, commercial lease agreements, and state government contracts require proof of CGL coverage. While the legal minimum required by the PA Home Improvement Consumer Protection Act (HICPA) is only $50,000 for personal injury and property damage, $1 million per occurrence and $2 million aggregate is the industry standard and the "practical floor" required by most commercial landlords, state government contracts, and general contractors.
The Pennsylvania Insurance Department also keeps a close eye on how carriers price these policies. Under Notice 2026-07, effective April 12, 2026, the department modernized filing requirements while keeping CGL and Businessowners Policies classified as "regulated". That means insurers must submit rates for prior approval, and those rates can't be excessive, inadequate, or unfairly discriminatory. This regulatory structure gives Pennsylvania business owners some protection against wildly inflated premiums.
On the legal side, Pennsylvania's Fair Share Act (Act 17 of 2011) limits defendants to paying only their proportional share of fault in many civil cases. Recent court rulings like Spencer v. Johnson have
narrowed the Act's application to cases where the plaintiff shares some fault, and legislative efforts through House Bill 2390 aim to
restore broader proportional liability protections. For business owners, this means your liability exposure could shift depending on how these legal changes play out.
By: Tyler Reitz
Managing Principal of Bowmans Insurance
What General Liability Covers (and What It Doesn't)
A CGL policy isn't a catch-all. It covers specific categories of risk, and knowing those boundaries prevents expensive surprises.
Bodily Injury and Property Damage Claims
This is the core of any general liability policy. If a third party, someone who doesn't work for you, suffers a physical injury or has their property damaged because of your operations, your CGL policy responds. That includes medical bills, lost wages, pain and suffering claims, and the cost of repairing or replacing damaged property.
Your policy also covers completed operations. If you're a contractor and a deck you built six months ago collapses, the bodily injury and property damage from that failure falls under your CGL. This is a critical distinction, because many claims don't surface until well after the work is done.
Personal and Advertising Injury Protection
CGL policies include a lesser-known coverage called "personal and advertising injury." This protects you against claims of libel, slander, false arrest, wrongful eviction, and copyright infringement in your advertising. A Harrisburg marketing firm that accidentally uses a copyrighted image in a client campaign could trigger this coverage. It's not the headline feature of a CGL policy, but it fills a real gap.
What CGL doesn't cover is equally important. Your own injuries and your employees' injuries aren't included: that's workers' compensation territory. Professional errors and omissions fall under a separate policy. Auto accidents involving business vehicles require commercial auto coverage. And intentional acts, criminal behavior, and pollution-related claims are almost always excluded.
Comparing Coverage: General Liability vs. Professional Liability
One of the most common mistakes small business owners make is assuming their general liability policy covers professional mistakes. It doesn't. These are two distinct policies that protect against different types of claims.
Comparison Chart: Which Policy Covers Which Risk?
| Risk Scenario | General Liability (CGL) | Professional Liability (E&O) |
|---|---|---|
| Customer slips and falls at your office | Covered | Not covered |
| Your work damages a client's property | Covered | Not covered |
| You give bad advice that costs a client money | Not covered | Covered |
| A subcontractor injures a bystander | Covered (with proper additional insured endorsement) | Not covered |
| You miss a project deadline, causing financial loss | Not covered | Covered |
| Your ad infringes on a competitor's copyright | Covered | Not covered |
| A design error leads to structural failure | May be covered (completed operations) | Covered |
If your business provides any kind of advice, design, consulting, or professional service, you likely need both policies. A general contractor in Harrisburg might carry CGL for on-site injuries and property damage, plus professional liability for design-build errors. An IT consultant needs CGL for client visits and E&O for software implementation failures.
Factors Influencing Insurance Costs in Central PA
Premiums for general liability insurance in Harrisburg vary widely based on several factors. Understanding what drives your cost helps you make smarter purchasing decisions.
Industry Classification and Risk Levels
Your industry classification code is the single biggest factor in your premium. A roofing contractor pays significantly more than an accounting firm because the physical risk profile is completely different. Insurers assign each business a class code based on its primary operations, and that code determines your base rate.
High-risk trades like demolition, excavation, and electrical work carry the steepest premiums. Lower-risk businesses, such as office-based consultants or bookkeepers, pay far less. If your business spans multiple trades, your insurer will assign codes to each operation and weight them by revenue.
Business Size and Annual Revenue Impact
Premiums scale with your revenue and payroll. A sole proprietor landscaper with $150,000 in annual revenue will pay a fraction of what a landscaping company with $2 million in revenue and 15 employees pays. Insurers use revenue as a proxy for exposure: more revenue generally means more client interactions, more job sites, and more opportunities for something to go wrong.
Your claims history matters too. A clean loss record over three to five years can earn you lower rates, while frequent claims, even small ones, signal higher risk. One thing to keep in mind: the Harrisburg Regional Chamber & CREDC offers a Member Value Program that has returned over $2.3 million in dividends on business insurance premiums to local participants. Group purchasing programs like this can meaningfully reduce your costs.
Common Questions About Harrisburg Business Insurance
Do I need insurance if I work from my home in Harrisburg? Yes. Working from home doesn't eliminate liability. Your homeowner's policy won't cover business-related claims. If a client visits your home office and gets injured, or if your business operations cause damage to a neighbor's property, you need a separate CGL policy.
How much coverage do most local contractors carry? While the statutory minimum for residential contractors under HICPA is $50,000, most Harrisburg contractors carry $1 million per occurrence and $2 million aggregate to meet industry standards. Larger commercial projects and government contracts often require higher limits, which you can achieve through an umbrella or excess liability policy layered on top of your base CGL.
Will my policy cover my employees if they get hurt? No. General liability only covers third parties. Employee injuries are handled through workers' compensation insurance, which Pennsylvania requires for most employers. These are separate policies with separate premiums.
Does this cover me if I make a mistake in my professional advice? No. Professional errors, omissions, and bad advice fall under professional liability (E&O) insurance. Your CGL policy covers physical injury and property damage, not financial losses from professional mistakes.
How do I get a certificate of insurance for a new contract?
Contact your insurance agent or carrier and request a certificate of insurance (COI). Most agents can issue one within 24 hours. If the contract requires the hiring party to be listed as an additional insured, your agent will add an endorsement to your policy. This is standard practice for subcontractor agreements and commercial leases in Harrisburg.
Making the Right Choice for Your Business
General liability insurance in Harrisburg isn't a luxury or a formality. It's the policy that stands between your business and a lawsuit that could wipe out years of hard work. The right coverage depends on your industry, your revenue, and the contracts you're pursuing.
Start with the standard $1 million/$2 million limits, then evaluate whether your specific operations or contract requirements call for higher coverage. Pair your CGL with workers' compensation if you have employees, and add professional liability if you provide any form of advice or design services. Review your policy annually, especially after adding new services, hiring staff, or taking on larger projects.
Talk to an independent insurance agent who understands the Harrisburg market and Pennsylvania's regulatory environment. They can match your actual risk profile to the right coverage structure, not just sell you a generic policy. Your business deserves protection that fits the way you actually operate.
ABOUT THE AUTHOR:
TYLER REITZ, CIC, CPCU, ARM, AU
As Managing Principal of Bowmans Insurance, I’m passionate about helping businesses and individuals protect what matters most with clarity and confidence. With advanced designations including CIC, CPCU, ARM, and AU, I bring a comprehensive approach to risk management—ensuring every client receives strategic, reliable, and personalized coverage.
Contact Us
Why Work With Us?
Why Choose Bowman Insurance Group for Personal Insurance?

Choice and Transparency
Bowman Insurance Group works for you, not the insurance providers. We offer a wide selection of policies from reputable insurers, giving you options that suit your unique needs. We prioritize clarity and honesty, ensuring you understand each policy’s benefits and limitations.

Your Personal Advocate
Our team is committed to more than policy sales—we’re here to serve as your advocate. We balance your coverage needs with affordability, working to provide you with the best value without compromise. Every decision we support is made with your best interests in mind.

Expert Guidance for Life
Insurance can feel complex, but we’re here to make it simple. With years of experience, our advisors explain policies clearly and keep you informed of relevant changes. You’ll receive consistent support from trusted professionals who understand your needs and are dedicated to helping you make informed choices.
About Bowman's Insurance Group
Over 100 years Delivering Exceptional Service to Our Community
Personal Insurance Coverage in Pennsylvania
Personal Insurance Solutions in Pennsylvania
Home
Insurance
Auto
Insurance
Umbrella
Insurance
Condo
Insurance
Boat
Insurance
Motorcycle Insurance
RV
Insurance
ATV
Insurance
Insurance Client Reviews
Read our
customer reviews

40+
Insurance Partners
98%
Client Retention Rate
100
Years in Business
98%
Satisfaction Rate
Process of Working With A Personal Insurance Agent in Pennsylvania
Step 1: Initial Assessment
Our process begins with a comprehensive review of your personal insurance needs. We’ll assess factors like your lifestyle, family needs, and assets, so you get the coverage that best suits your unique situation.
Step 2: Customized Consultation
Meet with our knowledgeable agents one-on-one to discuss options tailored to your requirements. We aim to clarify your choices and recommend the most suitable coverage, considering both quality and affordability.
Step 3: Policy Selection & Activation
Once we identify the right coverage, we’ll handle the paperwork and activate your policy. Our team ensures a smooth, straightforward process, giving you confidence and peace of mind in your coverage.
Our Experts
Meet Our Team of Professional Insurance Experts
Tyler Reitz CIC, CPCU, ARM, AU
President
Carmen Donachy, CISR
Treasurer and Customer Service Rep
Brian Brassell, CSA, CRPC
Investment Advisor Representative, Director of Financial Services Division
Kassie Swope, CIC, CISR, AINS
Commercial Department Manager
Our News & Blogs
Latest insurance news & blogs